How many washer turns per day does a laundromat need?
Translate paid washer turns and the realized wash-and-dry basket into revenue, contribution and a daily break-even threshold.
Work through the guide →
Validate the machine-size mix, paid turns and installed utility scope before accepting a laundromat lease or equipment deposits. The stated national wage scenario uses 145 paid washer turns per day at $9.00 per paid washer turn, producing $3,068 mature monthly EBIT and $550,789 modeled opening funding. Sales, capacity and nonwage costs remain planning assumptions.

Observe paid use by size and time of day, then reconcile washers, dryers and customer circulation. Available machine cycles create a ceiling; repeat demand and the realized wash-and-dry basket determine earned revenue.
One paid washer start carries its associated drying revenue in the basket. Dryer cycles and several machines used by one customer do not become additional washer-turn units.
At the assumed activity, the mature month produces $9,818 EBITDA, $3,068 EBIT and $7,318 cash after maintenance. The first twelve modeled months generate $38,123 of operating cash; they do not represent a full year at the mature run rate.
The EBIT threshold is approximately 130.05 paid washer turns per day; it uses the same price, variable-cost basis and complete paid roster. The listed ceiling is 216 paid washer turns per day, with the operating qualifications in the capacity explanation below. Check peak washer sizes, paired dryer load, cycle times, downtime and utility availability together. A full washer bank can still lose completions when drying or customer movement binds.
| Test | Entered activity or cost | Monthly EBIT |
|---|---|---|
| Published reference | 145 paid washer turns per day | $3,068 |
| 20% less earned activity | 116 paid washer turns per day | -$2,883 |
| 10% higher wage benchmarks | 1.10 × the same occupational wage anchors | $2,044 |
| 20% higher occupancy cost | $6,600.00 monthly occupancy | $1,968 |
Of the three separate tests shown, 20% less earned activity makes the largest change to monthly EBIT: -$5,951. This is a result of the stated test sizes, not a probability or a universal risk ranking.
Paid attendant, cleaning, management, reconciliation and vendor coordination remain in the plan even when customers operate the machines themselves.
Opening payments of $492,702, the deepest cumulative operating cash deficit of $18,215 in month 3, and the retained buffer of $39,873 add to $550,789 modeled funding. Refundable deposits are included in opening cash uses; they are not operating expenses. Funding is a scenario total, not a quote or a financing recommendation.
The mature maintenance allowance is a cash outflow alongside utilities and payroll. Positive mature cash does not establish recovery of the large installed opening payment within the model horizon.
EBITDA pays the full modeled roster and operating costs. EBIT also deducts depreciation. Mature cash deducts maintenance investment from EBITDA, after receivables stop growing. All three exclude financing, income taxes and additional owner distributions.
If paid turns or the wash-and-dry basket fall short, or an unresolved utility upgrade expands the commitment, revise the machine mix or site before paying nonrefundable deposits. Observe ordinary weekday and weekend paid use, then obtain a measured utility survey and delivered, installed machine quotation with landlord responsibilities assigned.
The wage observation is the BLS May 2025 national occupational median for each stated role. Hours, employer allowance, sales, prices, capacity and all nonwage costs are authored assumptions. Read the calculation definitions.
Calculations retain the exact input values. USD totals are displayed to whole dollars and blended prices to cents; activity and threshold estimates are displayed to up to two decimals. Rounded thresholds are estimates, not prescriptions for a sufficient whole job, visit or member count.
The reference unit is one paid washer start. Dryer revenue is included in the realized basket rather than counted as another washer turn. Record machine size, paid start, dryer attachment, discounts and refunds so the unit and revenue stay aligned.
Repeat use depends on availability, cleanliness, safety, machine reliability and a convenient customer path. Track returning payment accounts where available, but do not infer loyalty from the same customer occupying several machines in one visit.
| Format | What changes | How to use it |
|---|---|---|
| Attended self-service laundromat | Customers operate the machines; an attendant supports the floor and maintains the premises | The reference here uses 36 washers, paired gas-dryer capacity and paid coverage. |
| Unattended store | Remote controls and periodic service replace continuous floor coverage | Security, cleaning, response time and payroll need a separate operating plan. |
| Wash-and-fold laundry | Employees process customer loads as a production service | Labor, pricing, production capacity, collection and liability differ from self-service turns. |
A founder who is comfortable with a high initial equipment commitment, careful site diligence and routine operating controls. The work includes maintenance coordination, customer incidents, cleaning and cash or payment reconciliation even when customers run the machines.
The figures below are a national wage reference scenario. The paid roster uses May 2025 BLS national occupational medians. Prices, customer volume, rent, equipment and other commercial inputs are authored assumptions. This is not a researched average startup cost, owner-income promise or a funding recommendation.
| Input or result | Reference | What to verify |
|---|---|---|
| Completed sales units | 4,350 paid washer turns / month | 145 paid washer turns per day; demand requires evidence. |
| Net selling price | $9.00 | Build and test a relevant local menu, package or contract scope. |
| Revenue | $39,150 | Calculated volume × price, not observed sales. |
| Paid payroll | $10,236 / month | National wage medians × the stated hours × the 18% employer allowance. |
| Opening payments | $492,702 | Authored equipment and setup allowances, deposit and paid training. |
| Funding including reserve | $550,789 | Opening payments + deepest modeled operating deficit + retained buffer. |
| Mature operating profit (EBIT) | $3,068 / month | After the full paid roster and depreciation; before financing and income taxes. |
| Approximate EBIT threshold | Approximately 130.1 paid washer turns per day | A rounded estimate. Test whole permitted activity against the full roster and resource constraints. |
36 washers × 6 available turns per day = 216 paid washer turns per day. This is a simplified physical ceiling. Cycle mix, downtime, uneven peaks, dryer availability, customer dwell time and demand can all reduce usable throughput.
17% water, sewer, gas and electricity plus 7% payment fees, customer supplies and other costs that move with paid turns. Insurance $650; cleaning, security and waste $1,100; marketing $600; connectivity and software $350; pest control, accounting and other operating costs $1,500 per month. Maintenance investment is modeled separately at $2,500 per month.
Laundry and Dry-Cleaning Workers is the broad attendant proxy; General and Operations Managers covers paid management work. Neither occupation establishes a hiring quote. The 18% employer allowance is a planning assumption, not a payroll compliance calculation.
BLS May 2025 national wage workbook · Calculation definitions · How owner income differs from EBIT
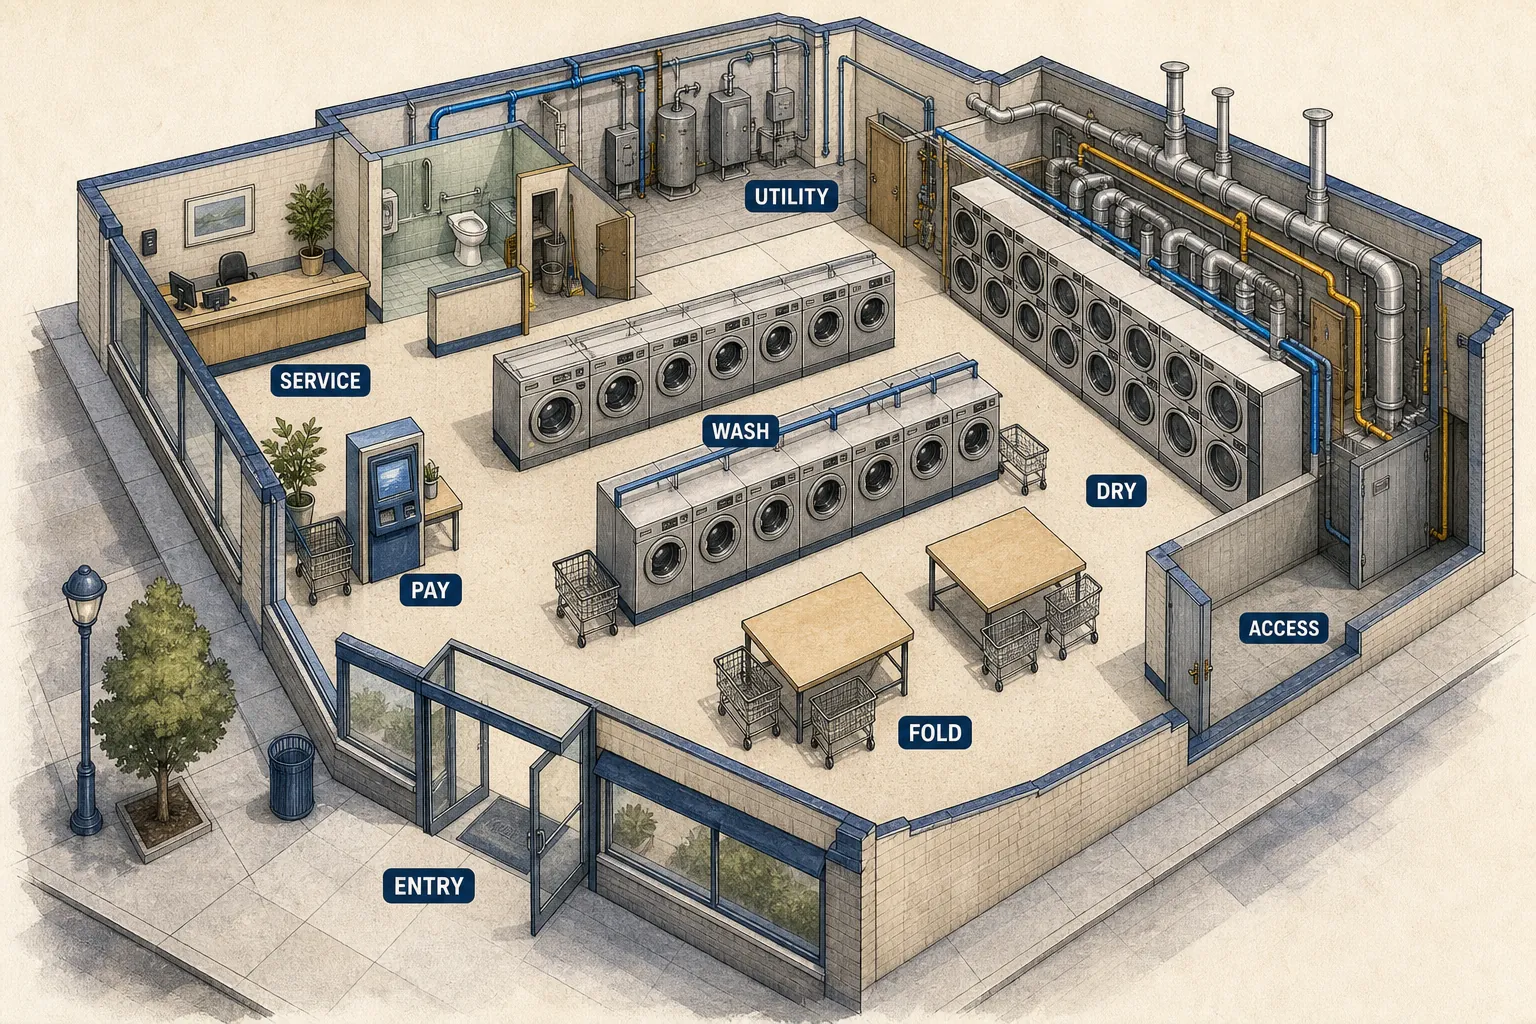
| Workstream | What the brief needs | Decision before spending |
|---|---|---|
| Washer and dryer bank | Machine sizes, cycle times, dryer ratio, foundations, exhaust and service clearances | Match the ordered mix to observed paid demand and a commissioned layout. |
| Water and energy systems | Supply pressure, hot water, drainage, sewer, gas, electrical load, make-up air and metering | Obtain written utility and contractor scopes before accepting the premises. |
| Customer and control systems | Payment, refunds, carts, folding, seating, accessibility, cameras and attendant station | Test the complete customer path and failure response before opening. |
Compare installed scope, exclusions and payment dates. Do not treat an unquoted item as zero or count a bundled installation twice. How to compare equipment quotes and build the opening budget explains a reusable quote ledger.
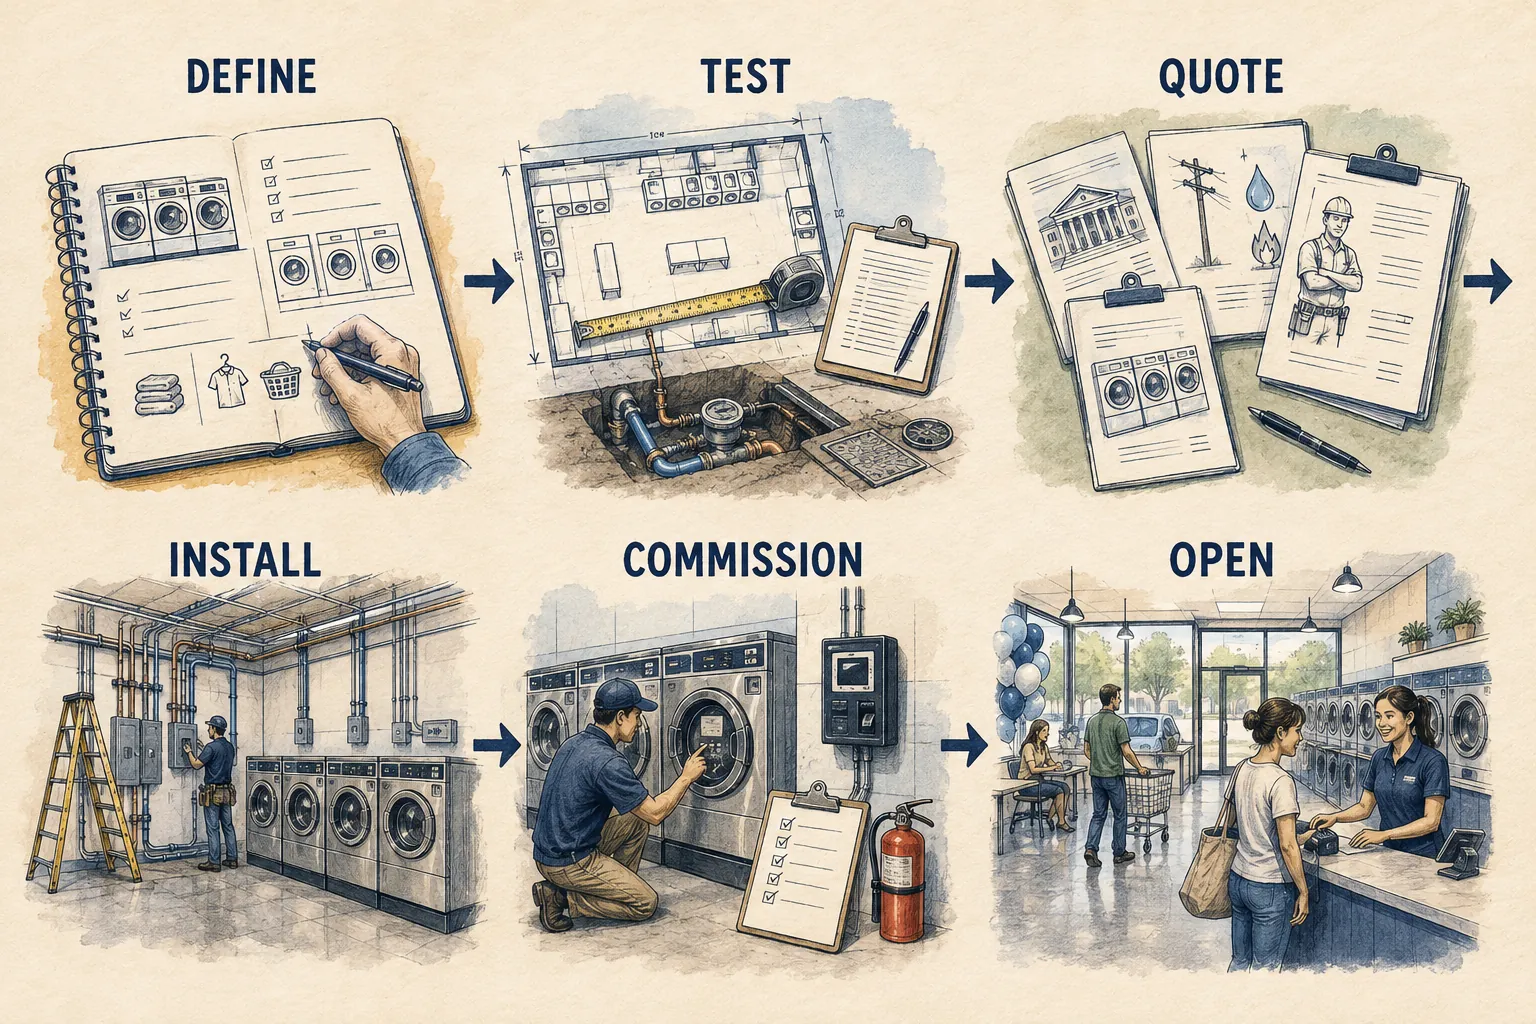
List each washer size and price, expected mix, dryer attachment and refund policy. Keep theoretical machine cycles separate from paid demand.
Measure the floor and trace water, sewer, gas, electrical, exhaust, structure and maintenance access. Record what the landlord, utility, contractor and equipment supplier each includes.
Combine equipment, freight, foundations, utility trunks, permits, deposits, commissioning and opening delay. Keep quoted items and planning allowances visibly separate.
Test every machine, payment path, shutoff, drain, exhaust and customer route. Train the paid attendant on cleaning, refunds, incidents and out-of-service controls.
| Measure | Why it changes a decision |
|---|---|
| Paid turns by machine size and hour | Shows whether the installed mix serves real demand rather than a single average. |
| Realized revenue per washer turn | Connects washer price, dryer attachment, discounts and refunds without double-counting units. |
| Utility cost and gallons per paid turn | Detects leaks, inefficient cycles and a variable-cost assumption that no longer holds. |
| Downtime, refunds and repeat use | Links reliability and customer experience to available capacity and retained demand. |
Review actuals against the scope you priced. If an extra service, new trading hour or more distant client changes the work, update the roster and contribution calculation before expanding.
Bring the measured floor plan, machine schedule, water and sewer demand, gas and electrical loads, exhaust and make-up air plan, structural scope, accessibility path, signage and operating hours. Ask the address-level planning, building, fire and utility authorities which reviews and upgrades apply.
Each state profile links to official registration, tax and employer routes, together with the questions still requiring an address-specific answer. How to find the permits and approvals your business actually needs provides the record to keep.
An unsigned utility-capacity answer, a lease that assigns major infrastructure ambiguously, or a sales plan that treats six daily cycles on every washer as guaranteed demand is a reason to stop before paying equipment deposits.
Write a response that changes the actual cause: narrower scope, a different site, revised paid staffing, a tested price or a delayed opening. A larger cash buffer only addresses a temporary timing gap.
Translate paid washer turns and the realized wash-and-dry basket into revenue, contribution and a daily break-even threshold.
Work through the guide →Trace water, sewer, gas, electrical, exhaust, structure and access from the proposed machine schedule into the lease and installed-cost plan.
Work through the guide →Compare equipment at installed usable scope, account for excluded costs and connect supplier payment terms to the opening cash plan.
Work through the guide →Create a weekly receipts-and-payments forecast, locate the cash low point and test late collections using an editable 13-week schedule.
Work through the guide →A restaurant coordinates food production and guest service; a laundromat coordinates an equipment-heavy site around paid machine turns. Both depend on a suitable address, but the critical technical and customer evidence is different.
Compare the operating choices →A coffee shop depends on frequent purchases in short buying windows. A laundromat depends on less frequent household visits with longer dwell time and a machine mix that can serve peak loads.
Compare the operating choices →Both businesses sell access to clean laundry or premises outcomes, but the cleaning business moves a paid team across client sites while the laundromat concentrates customers and equipment at one utility-intensive location.
Compare the operating choices →A salon sells scheduled practitioner time; a laundromat sells access to machines and a usable customer environment. Both need repeat customers, but capacity and service quality are created differently.
Compare the operating choices →A detailing studio uses technician-hours and bay time to complete individual vehicles. A laundromat lets customers operate machines, but depends on a larger machine bank, utility envelope and continuous availability.
Compare the operating choices →A laundromat sells access to reliable machines and a usable customer environment. A daycare center sells reserved care capacity supported by qualified people throughout the day.
Compare the operating choices →A laundromat sells customer access to installed machines. A pet grooming salon sells staff-delivered skilled appointments. Both use wet-service premises, but labor, customer involvement and the binding capacity are different.
Compare the operating choices →A laundromat concentrates installed machines and utilities at one customer-operated site. A landscaping company distributes trucks, equipment and paid crews across residential routes. Both require asset uptime, but their demand units and labor dependency differ.
Compare the operating choices →A Laundromat sells customer use of a large fixed machine bank across long opening hours. A Food Truck uses a small mobile kitchen and paid crew to produce each order in limited service windows. Both require equipment uptime, but labor dependence, perishability and site commitments differ.
Compare the operating choices →A Laundromat sells customer access to a fixed machine bank, while a Bakery uses equipment and paid production to create perishable goods for retail orders. Both can be utility-heavy, but customer operation, labor dependence and inventory loss differ.
Compare the operating choices →A Laundromat sells customer use of a machine bank across long opening hours. A Fitness Studio sells recurring access through a much narrower instructor-led timetable. Both require a reliable premises and repeat local use, but customer-operated cycles and paid classes produce different labor and peak-capacity economics.
Compare the operating choices →A Laundromat earns from customer-operated washer turns supported by installed machines, utilities, and a fixed site. An HVAC Company earns from paid technical field work supported by technicians, vehicles, tools, parts, and supplier access. One format concentrates capital in self-service equipment; the other ties capacity to qualified paid hours and route execution.
Compare the operating choices →A Laundromat earns from customer-operated washer turns supported by installed machines, utilities, and one location. A Moving Company earns from paid field projects supported by one truck and a three-person crew. One concentrates capital in self-service equipment; the other ties capacity to coordinated paid hours, route access, and custody.
Compare the operating choices →A Laundromat earns from paid washer turns and dryer use through customer-operated machines and utilities. An Auto Repair Shop earns from completed repair orders through skilled technicians, bays, labor, and parts. Both commit to equipment and premises, but labor intensity, customer authorization, inventory, custody, and quality recovery differ.
Compare the operating choices →A Laundromat earns from paid washer turns and dryer use through machine count, cycle time, utilities, uptime, and customer turns. A Plumbing Company earns from completed and collected residential service jobs through licensed plumbers, two vehicles, dispatch, materials, permits, and callback control. Both must fit paid capacity to realized contribution, while plumbing adds address-to-address travel, trade authority, water and gas system risk, material acquisition, and return-service exposure.
Compare the operating choices →A Laundromat earns from paid washer turns and dryer use through machine count, cycle time, utilities, uptime, and customer turns. An Electrical Contractor earns from completed and collected residential service and small-alteration jobs through licensed electricians, two vehicles, dispatch, sold hours, materials, permits, inspections, testing, and rework control. Both must fit paid capacity to realized contribution, while electrical adds address-to-address travel, trade authority, code and energized-work risk, material compatibility, inspection dependencies, and return-service exposure.
Compare the operating choices →Laundromat earns from paid washer turns and dryer use and is constrained by machine count, cycle time, utilities, uptime, and customer turns. Pest Control Company earns a monthly household-plan yield while delivering a separate calendar of inspections, initial visits and callbacks. Compare realized contribution and paid capacity in their own units; a pest contract base is useful only when retention, legal scope and route obligations remain deliverable.
Compare the operating choices →Laundromat earns from paid washer starts and attached drying revenue and is constrained by washer-size mix, dryers, utility capacity, uptime and peak customer circulation. Residential Remodeling Company earns accepted interior scope, expressed as comparable project equivalents, while controlling a paid carpenter crew and authorized specialty trades. Compare the complete paid operating mechanism and dated cash, using each format’s own unit.
Compare the operating choices →No. It is the simplified reference capacity ceiling. The published sales assumption is lower and still requires local observation and a machine-size mix.
No. It is an authored realized revenue assumption per paid washer turn, including the associated dryer mix and net of discounts and refunds. Build it from local prices and observed behavior.
No. Confirm retained equipment, service sizes, pipe condition, sewer route, gas, electrical, exhaust, structure, accessibility and code status for the proposed new machine schedule.
No states match these filters.
Sorting compares one defined format. It does not rank states for attractiveness or prove demand. Funding includes opening payments, the deepest cumulative operating cash deficit in the 60-month model and the retained cash buffer.
| State | Funding scenario | Loaded payroll / month | Approximate EBIT threshold paid washer turns per day |
|---|---|---|---|
| Alabama | $545,813 | $9,273 | 125.4 |
| Alaska | $553,930 | $10,844 | 133 |
| Arizona | $550,203 | $10,123 | 129.5 |
| Arkansas | $539,431 | $7,896 | 118.6 |
| California | $557,051 | $11,448 | 136 |
| Colorado | $558,353 | $11,700 | 137.2 |
| Connecticut | $558,107 | $11,653 | 137 |
| Delaware | $555,688 | $11,185 | 134.7 |
| Florida | $547,593 | $9,618 | 127 |
| Georgia | $546,343 | $9,376 | 125.9 |
| Hawaii | $551,990 | $10,469 | 131.2 |
| Idaho | $546,189 | $9,346 | 125.7 |
| Illinois | $550,666 | $10,212 | 129.9 |
| Indiana | $547,523 | $9,604 | 127 |
| Iowa | $546,546 | $9,415 | 126 |
| Kansas | $543,838 | $8,891 | 123.5 |
| Kentucky | $540,831 | $8,232 | 120.3 |
| Louisiana | $543,049 | $8,738 | 122.7 |
| Maine | $551,795 | $10,431 | 131 |
| Maryland | $552,932 | $10,651 | 132.1 |
| Massachusetts | $557,293 | $11,495 | 136.2 |
| Michigan | $549,776 | $10,040 | 129.1 |
| Minnesota | $552,081 | $10,486 | 131.3 |
| Mississippi | $543,726 | $8,869 | 123.4 |
| Missouri | $544,769 | $9,071 | 124.4 |
| Montana | $549,315 | $9,951 | 128.7 |
| Nebraska | $546,753 | $9,455 | 126.2 |
| Nevada | $550,806 | $10,240 | 130.1 |
| New Hampshire | $556,225 | $11,288 | 135.2 |
| New Jersey | $565,554 | $12,949 | 143.3 |
| New Mexico | $545,626 | $9,237 | 125.2 |
| New York | $555,704 | $11,188 | 134.7 |
| North Carolina | $547,270 | $9,555 | 126.7 |
| North Dakota | $551,742 | $10,421 | 130.9 |
| Ohio | $545,136 | $9,142 | 124.7 |
| Oklahoma | $541,728 | $8,448 | 121.3 |
| Oregon | $553,069 | $10,678 | 132.2 |
| Pennsylvania | $549,506 | $9,988 | 128.8 |
| Rhode Island | $555,185 | $11,087 | 134.2 |
| South Carolina | $546,693 | $9,444 | 126.2 |
| South Dakota | $554,826 | $11,018 | 133.9 |
| Tennessee | $549,439 | $9,975 | 128.8 |
| Texas | $545,370 | $9,187 | 124.9 |
| Utah | $550,021 | $10,088 | 129.3 |
| Vermont | $551,673 | $10,407 | 130.9 |
| Virginia | $551,301 | $10,335 | 130.5 |
| Washington | $560,527 | $12,121 | 139.2 |
| West Virginia | $541,121 | $8,302 | 120.6 |
| Wisconsin | $553,999 | $10,858 | 133.1 |
| Wyoming | $543,741 | $8,872 | 123.4 |
Published research and calculations support business planning and education. They are not personalized financial, investment, tax or legal advice, and they do not guarantee costs, revenue, profit or financing. Estimates depend on the stated format, location, source periods and assumptions. Check the requirements and commitments that apply to your circumstances.