Can vending sales cover stock, the paid route and machine investment?
The ten-machine reference sells 6,000 paid items monthly at $2.50 net each. After product cost, assumed host/payment charges and the complete paid roster, it produces about $765 EBITDA, negative $627 EBIT and $565 cash after capital maintenance. Cash needs 5,423 whole monthly paid vends; EBIT needs 6,642 with unchanged costs. Both fit the disclosed 8,000-vend capacity, but neither threshold establishes purchases at an accepted site.
What you will produce: One machine-to-item contribution calculation, three financial thresholds, a stock/route/repair capacity check and opening funding tied to the same 60-month cash schedule.
Updated October 20, 2026 · Worked examples and editable worksheets
What to have ready
Bring accepted site agreements, exact machine and payment configuration, item acquisition costs and tax treatment, successful item sales, refunds/losses, commission and provider terms, a dated service route, paid hours/wages, installation quotes and supplier/settlement dates.
Work through the calculation and decision
Define one successful paid item and one accepted site
An item-vend is one product successfully supplied for payment. Count each item once. A cashless authorization, a free replacement and a refunded failed dispense do not create additional completed paid vends. If a checkout can contain several items, reconcile its items to its price and payment charges before using a per-item average.
The reference is ten indoor combination machines at ten accepted third-party sites, selling packaged snacks and drinks for 30 available days each month. Twenty successful paid item-vends per machine-day create 6,000 monthly sales. Every number in that multiplication is an assumption. A machine bought, a proposed placement, footfall or employee count does not establish paying customers.
Census: 2022 NAICS 445132 vending machine operators · 2022 industry definition · Checked 2026-10-20
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Reconcile product purchases, sold cost and inventory loss
The assumed acquisition cost is $1.10 per item and loss is 2% of acquired items. To supply one paid item after that loss, the model acquires 1 ÷ 0.98 items. Product cost per paid vend is therefore $1.10 ÷ 0.98, or approximately $1.122449. Do not also subtract 2% of sales: that would charge an unmatched second loss.
At 6,000 paid vends, sold-product cost is $6,600 and expected inventory-loss expense is approximately $135, totaling $6,735 replacement purchases. Expected lost items can be fractional in a forecast; the actual stock ledger records whole items by batch, reason and machine. The $3,000 opening combined machine/warehouse stock balance is funded once and then held constant through replacement purchases. The linear loss assumption includes no additional calendar-driven expiry or stock build; unsold items expiring during a slow month can require extra dated cash and expense. Extra stock or supplier credit changes dated cash separately.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Convert the selling price into retained contribution
The $2.50 price is realized net product revenue after refunds and applicable sales tax. The model then deducts a 10% host commission and 6% blended payment allowance on that net basis, plus product cost. Contribution is $2.50 × (1 − 0.10 − 0.06) − $1.10 ÷ 0.98, or approximately $0.977551 per paid item. At the default sales level, location commissions are $1,500 and payment costs $900 monthly.
The host and provider percentages are assumptions, not quoted terms. Actual contracts can charge commission on gross tax-inclusive receipts, fixed cents per transaction, a cashless-only share, monthly subscriptions, network/minimum fees or other costs. Compute their matched effective cost before replacing an input. Subscriptions are in standing costs; they do not replace transaction charges. California and Texas official guidance illustrate why product classification and jurisdiction must be resolved before turning displayed consumer prices into net revenue.
California CDTFA: applying and reporting vending-machine tax · Guidance checked October 20, 2026 · Checked 2026-10-20
Texas Comptroller: Rule 3.293 food and vending sales · Rule text checked October 20, 2026 · Checked 2026-10-20
Nayax: VPOS Touch direct device offer · Offer checked October 20, 2026 · Checked 2026-10-20
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Pay the complete route, technical work and management
The reference pays 104 monthly driver/sales hours, 12 technical repair hours and 17.33 management hours. May 2025 national occupation medians of $18.64, $22.81 and $50.85 per hour anchor replacement cost; an assumed 18% employer addition produces $3,650.5424 monthly payroll. Owner operation does not erase the time or cost. A base occupation wage is not a qualified contractor quote or an owner distribution.
Storage occupancy of $450 and $1,000 other standing costs make the full monthly fixed operating boundary $5,100.5424. The standing allowance includes vehicle costs, reader/telemetry subscriptions, business insurance, administration and routine materials. Paid repair labor is separate from materials and the $200 capital-maintenance cash allowance. Match all inclusions before combining provider, vehicle, repair or insurance quotes.
BLS May 2025 national occupation wage workbook · May 2025
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Name and test all three financial thresholds
EBITDA subtracts the full paid roster and standing operating costs. Depreciation-inclusive EBIT also subtracts $83,500 ÷ 60, or approximately $1,392 monthly depreciation. Cash after capital maintenance instead subtracts the $200 maintenance cash allowance; settlement movement is then handled in each forecast month. A smaller cash allowance does not establish that future machine and vehicle replacement is adequately funded.
The continuous EBITDA, cash and EBIT thresholds are approximately 5,217.67, 5,422.27 and 6,641.30 paid monthly vends. At the whole-sale boundary, 5,423 vends produce positive cash after maintenance while 5,422 do not; 6,642 produce nonnegative EBIT while 6,641 do not. These hold price, product mix, loss, fees and paid costs fixed. They are financial boundaries, not observed demand or a recommended sales cushion. The default 6,000-vend month remains EBIT-negative.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Solve every resource at the proposed sales ceiling
Six visits at each of ten machines make 60 stops. The recurring calendar must actually maintain the assumed five-day maximum gap; the visit count alone is insufficient. At 180 usable stocked positions per machine, expected acquired-item loss also consumes the stock supply. Equal sales and the same product mix imply a stock ceiling of 10,584 paid monthly vends. Wanted selections can sell out earlier despite spare nominal positions.
Route workload is 12 standing hours + 60 × (0.5 service + 0.3 driving/access) + paid vends × (0.003 product handling + 2% × 0.06 incident recovery). Repair is two standing hours + paid vends × 0.5% × 0.25 recovery hour. Management is eight standing hours + 0.0001 hour per vend. At 8,000 vends, those clocks use 93.6, 12 and 8.8 hours. Vend 8,001 needs 12.00125 repair hours, so the 12-hour repair pool binds before route time or stock. Expected recovery is recalculated at the proposed maximum, including when current sales are zero.
The route incident allowance averages 0.06 paid hour for customer triage, access, collection and extra driving across its assumed event mix; it is not a promise that every recovery trip takes 3.6 minutes. The technical pool adds 0.25 hour for diagnosis/repair, with incident driving already in the route pool. A shared event may draw on both pools for distinct work; count the same work only once. These ratios are workload assumptions per successful paid vend, not measured failure probabilities.
An aggregate ceiling is conditional on actual site access, product mix, route sequence, vehicle payload and handling limits, safe work, equipment condition and available repair support. It cannot establish an individual diary or guarantee uptime. Test the busiest machine and a restricted-access stop separately; adding cash does not supply missing paid time.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
eVending: USI Futura 29-selection combination machine · Offer checked October 20, 2026 · Checked 2026-10-20
Fund opening stock, installed assets and the launch deficit
The $95,000 opening allowances include ten assumed $6,500 delivered payment-ready machine hardware packages, excluding host-site electrical and anchoring work. A separate $4,000 allowance covers that host-site work. The total also includes a used route vehicle, storage/handling assets, $3,000 product inventory, business setup, launch and contingency. Add the $900 refundable storage deposit and approximately $1,095 paid pre-opening training for $96,995 total opening payments. A manufacturer list price is a scope-limited equipment observation, not this complete installed route quote.
The forecast assumes 40/55/70/82/90/96/100% of mature sales from opening, with the full roster and scheduled visits retained. A two-day net-sales settlement receivable delays cash. The deepest cumulative operating deficit is approximately $7,637 in month 5; the retained two-month standing-cost buffer is $10,201. Opening payments plus that deficit and buffer total approximately $114,833. The ramp is an assumption about successful paid purchases, not a forecast derived from machine capacity.
eVending: USI Futura 29-selection combination machine · Offer checked October 20, 2026 · Checked 2026-10-20
Nayax: VPOS Touch direct device offer · Offer checked October 20, 2026 · Checked 2026-10-20
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Stress net price and read the complete cash schedule
A 10% net-price fall leaves item acquisition cost and the paid roster unchanged. The $2.25 realized sale produces approximately negative $695 monthly cash after capital maintenance at the same 6,000 vends, compared with positive $565 at $2.50. Changing payment terms, host basis, product loss, travel or repair scope can also reverse the decision; test each from a consistent input snapshot.
First-year operating cash after capital maintenance and settlement movement is approximately negative $4,018. The default does not recover opening cash within 60 months, even though its mature cash month is positive. The JSON and CSV carry the same valid inputs, capacity flags and all 60 stock-cost/earning/cash rows. Blank or disallowed edits clear current results; reset restores exact defaults. Month-end balances can understate the daily gap between supplier payments, payroll, host remittance and card settlement. Keep tax, financing and owner withdrawals outside this stated operating boundary.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Ten accepted machine locations with 6,000 assumed paid monthly vends
Wage medians are observations. Every commercial input, location, productivity rate and sales assumption below is authored teaching material.
| Input or result | Reference | What the number establishes |
|---|---|---|
| Machines / selling activity | 10 × 30 days × 20 paid item-vends = 6,000 | Assumed successful paid sales; no observed demand |
| Net price / acquired-item cost | $2.50 / $1.10 | Net price excludes refunds and tax; cost precedes acquired-item loss |
| Acquired-item loss / commission / payment | 2% / 10% / 6% | Distinct denominators; no quoted host/provider terms |
| Net revenue / product cost | $15,000 / approximately $6,735 | Product cost includes expected loss once |
| Loaded paid roster / standing boundary | Approximately $3,651 / $5,101 | Owner replacement work remains paid |
| EBITDA / EBIT / cash after maintenance | $765 / negative $627 / $565 | Distinct definitions before financing and income tax |
| Whole monthly cash / EBIT thresholds | 5,423 / 6,642 paid vends | Previous whole increment fails; both fit conditional capacity |
| Complete paid-resource ceiling | 8,000 paid vends / month | Repair uses all 12 paid hours; next vend fails |
| Opening payments / total funding | Approximately $96,995 / $114,833 | Inventory, deposit, launch deficit and buffer are separate |
| First-year cash / opening recovery | Approximately negative $4,018 / none within 60 months | Mature surplus is not opening payback |
What this changes: The route needs accepted-site paid sales and retained net contribution strong enough to cover the complete paid operation and asset commitment. A positive cash month alone does not establish that result.
Illustrative amounts are rounded for display. Use the full inputs and stated units when recalculating; an approximate threshold is not itself a sufficient activity prescription.
Test vending contribution, complete paid route capacity and opening cash
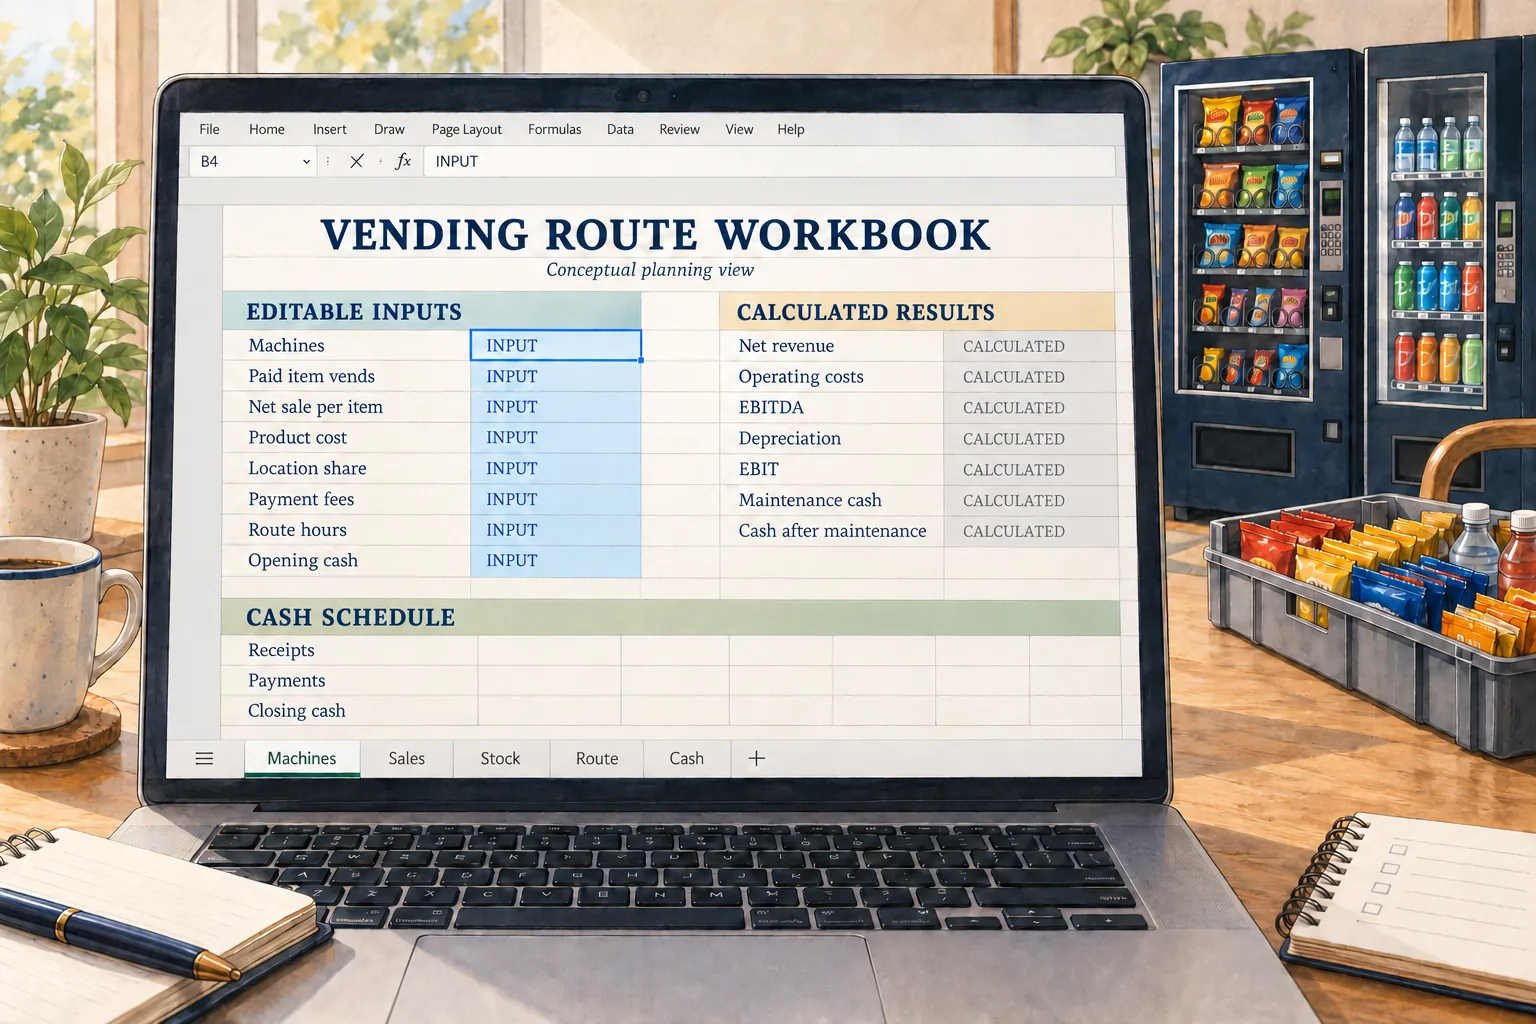
Start with the worked inputs, then change a value to test your own scenario. All money amounts are in USD. The result updates in this tab.
Calculations keep the full entered precision; displayed amounts are rounded independently. A blank, out-of-range or disallowed fractional count clears the result. Reset example restores the exact worked inputs. JSON and CSV downloads contain that same valid scenario; the worksheet download also includes your evidence and decision.
Illustrative result · assumptions apply
- Completed paid item-vends in the mature month
- 6,000 item-vends / month
- Replenishment visits across the route
- 60 visits / month
- Mature monthly net revenue
- $15,000.00
- Product cost per paid vend including acquired-item loss
- $1.12
- Sold-product acquisition cost
- $6,600.00
- Inventory-loss expense
- $134.69
- Replacement inventory purchases, with unchanged inventory balance
- $6,734.69
- Location commissions
- $1,500.00
- Payment-cost allowance
- $900.00
- Contribution per paid item-vend
- $0.98
- Loaded monthly paid roster including owner replacement work
- $3,650.54
- Mature monthly EBITDA
- $764.76
- Mature monthly EBIT after depreciation
- -$626.90
- Mature monthly cash after capital maintenance before settlement changes
- $564.76
- Approximate EBITDA threshold
- 5,217.67 paid item-vends / month
- Approximate cash-after-maintenance threshold
- 5,422.27 paid item-vends / month
- Approximate depreciation-inclusive EBIT threshold
- 6,641.3 paid item-vends / month
- Minimum whole monthly paid vends for nonnegative cash after maintenance, financial boundary only
- 5,423 paid item-vends / month
- Minimum whole monthly paid vends for nonnegative EBIT, financial boundary only
- 6,642 paid item-vends / month
- Maximum whole monthly paid vends from the entered stock and complete paid clocks
- 8,000 paid item-vends / month
- Route workload at that ceiling
- 93.6 person-hours
- Repair workload at that ceiling
- 12 person-hours
- Management workload at that ceiling
- 8.8 person-hours
- Opening product inventory, a cash use and continuing asset balance
- $3,000.00
- Refundable storage deposit
- $900.00
- Paid pre-opening training
- $1,095.16
- Total opening payments
- $96,995.16
- Deepest cumulative operating cash deficit
- $7,636.63
- Month of deepest deficit; zero means none
- 5 month
- Cash buffer retained above that deficit
- $10,201.08
- Opening funding including operating reserve
- $114,832.88
- First-year operating cash after maintenance and settlement movement
- -$4,017.90
- Sustained opening-cash recovery within 60 months; unavailable means none
- Not available
- Cash at the minimum whole-vend cash threshold, before settlement changes
- $0.72
- EBIT at the minimum whole-vend EBIT threshold
- $0.68
The three thresholds hold net price, item mix, loss, commission, payment allowance and the complete paid roster fixed. Entered sales fit the disclosed aggregate stock, route, repair and management clocks. The stock ceiling assumes equal sales per machine and a recurring calendar that actually maintains the maximum gap; a busier machine, unavailable item, restricted site access, shelf life or failed equipment can impose a lower limit. Incident recovery rises with proposed sales. One paid item-vend earns one product sale; multi-item baskets and refunded failed attempts are not extra completed vends. Net price excludes sales tax and refunds. Commission and payment rates are budget assumptions on net revenue, not provider quotes. The 2% default loss is a share of acquired items and is charged once. Opening inventory is funded once and held constant through replacement purchases; increasing stocks or supplier credit needs a separate dated cash adjustment. The 40/55/70/82/90/96/100% sales ramp is assumed demand. The 60-month schedule measures month-end cash; daily settlement and supplier gaps may be greater. Financing, income tax and owner distributions are excluded.
| Month | Paid item-vends | Net sales | Acquired replacement items | Lost acquired items | Sold-product cost | Inventory-loss expense | Replacement purchases | Location commissions | Payment costs | EBITDA | Depreciation | EBIT | Capital maintenance cash | Product inventory balance | Inventory increase | Settlement receivable | Receivable increase | Operating cash | Cumulative operating cash | Funded closing cash | Route hours | Repair hours | Management hours | Stock and paid work fit (1=yes; 0=no) |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | 2,400 | $6,000.00 | 2,448.98 | 48.98 | $2,640.00 | $53.88 | $2,693.88 | $600.00 | $360.00 | -$2,754.42 | $1,391.67 | -$4,146.09 | $200.00 | $3,000.00 | $0.00 | $400.00 | $400.00 | -$3,354.42 | -$3,354.42 | $14,483.30 | 70.08 | 5 | 8.24 | 1 |
| 2 | 3,300 | $8,250.00 | 3,367.35 | 67.35 | $3,630.00 | $74.08 | $3,704.08 | $825.00 | $495.00 | -$1,874.62 | $1,391.67 | -$3,266.29 | $200.00 | $3,000.00 | $0.00 | $550.00 | $150.00 | -$2,224.62 | -$5,579.04 | $12,258.67 | 73.86 | 6.13 | 8.33 | 1 |
| 3 | 4,200 | $10,500.00 | 4,285.71 | 85.71 | $4,620.00 | $94.29 | $4,714.29 | $1,050.00 | $630.00 | -$994.83 | $1,391.67 | -$2,386.49 | $200.00 | $3,000.00 | $0.00 | $700.00 | $150.00 | -$1,344.83 | -$6,923.87 | $10,913.84 | 77.64 | 7.25 | 8.42 | 1 |
| 4 | 4,920 | $12,300.00 | 5,020.41 | 100.41 | $5,412.00 | $110.45 | $5,522.45 | $1,230.00 | $738.00 | -$290.99 | $1,391.67 | -$1,682.66 | $200.00 | $3,000.00 | $0.00 | $820.00 | $120.00 | -$610.99 | -$7,534.86 | $10,302.85 | 80.66 | 8.15 | 8.49 | 1 |
| 5 | 5,400 | $13,500.00 | 5,510.2 | 110.2 | $5,940.00 | $121.22 | $6,061.22 | $1,350.00 | $810.00 | $178.23 | $1,391.67 | -$1,213.43 | $200.00 | $3,000.00 | $0.00 | $900.00 | $80.00 | -$101.77 | -$7,636.63 | $10,201.08 | 82.68 | 8.75 | 8.54 | 1 |
| 6 | 5,760 | $14,400.00 | 5,877.55 | 117.55 | $6,336.00 | $129.31 | $6,465.31 | $1,440.00 | $864.00 | $530.15 | $1,391.67 | -$861.52 | $200.00 | $3,000.00 | $0.00 | $960.00 | $60.00 | $270.15 | -$7,366.48 | $10,471.24 | 84.19 | 9.2 | 8.58 | 1 |
| 7 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $40.00 | $524.76 | -$6,841.72 | $10,996.00 | 85.2 | 9.5 | 8.6 | 1 |
| 8 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$6,276.95 | $11,560.76 | 85.2 | 9.5 | 8.6 | 1 |
| 9 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$5,712.19 | $12,125.53 | 85.2 | 9.5 | 8.6 | 1 |
| 10 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$5,147.42 | $12,690.29 | 85.2 | 9.5 | 8.6 | 1 |
| 11 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$4,582.66 | $13,255.05 | 85.2 | 9.5 | 8.6 | 1 |
| 12 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$4,017.90 | $13,819.82 | 85.2 | 9.5 | 8.6 | 1 |
| 13 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$3,453.13 | $14,384.58 | 85.2 | 9.5 | 8.6 | 1 |
| 14 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$2,888.37 | $14,949.35 | 85.2 | 9.5 | 8.6 | 1 |
| 15 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$2,323.61 | $15,514.11 | 85.2 | 9.5 | 8.6 | 1 |
| 16 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$1,758.84 | $16,078.87 | 85.2 | 9.5 | 8.6 | 1 |
| 17 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$1,194.08 | $16,643.64 | 85.2 | 9.5 | 8.6 | 1 |
| 18 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$629.31 | $17,208.40 | 85.2 | 9.5 | 8.6 | 1 |
| 19 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | -$64.55 | $17,773.16 | 85.2 | 9.5 | 8.6 | 1 |
| 20 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $500.21 | $18,337.93 | 85.2 | 9.5 | 8.6 | 1 |
| 21 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $1,064.98 | $18,902.69 | 85.2 | 9.5 | 8.6 | 1 |
| 22 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $1,629.74 | $19,467.46 | 85.2 | 9.5 | 8.6 | 1 |
| 23 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $2,194.50 | $20,032.22 | 85.2 | 9.5 | 8.6 | 1 |
| 24 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $2,759.27 | $20,596.98 | 85.2 | 9.5 | 8.6 | 1 |
| 25 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $3,324.03 | $21,161.75 | 85.2 | 9.5 | 8.6 | 1 |
| 26 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $3,888.80 | $21,726.51 | 85.2 | 9.5 | 8.6 | 1 |
| 27 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $4,453.56 | $22,291.27 | 85.2 | 9.5 | 8.6 | 1 |
| 28 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $5,018.32 | $22,856.04 | 85.2 | 9.5 | 8.6 | 1 |
| 29 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $5,583.09 | $23,420.80 | 85.2 | 9.5 | 8.6 | 1 |
| 30 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $6,147.85 | $23,985.57 | 85.2 | 9.5 | 8.6 | 1 |
| 31 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $6,712.61 | $24,550.33 | 85.2 | 9.5 | 8.6 | 1 |
| 32 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $7,277.38 | $25,115.09 | 85.2 | 9.5 | 8.6 | 1 |
| 33 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $7,842.14 | $25,679.86 | 85.2 | 9.5 | 8.6 | 1 |
| 34 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $8,406.91 | $26,244.62 | 85.2 | 9.5 | 8.6 | 1 |
| 35 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $8,971.67 | $26,809.38 | 85.2 | 9.5 | 8.6 | 1 |
| 36 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $9,536.43 | $27,374.15 | 85.2 | 9.5 | 8.6 | 1 |
| 37 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $10,101.20 | $27,938.91 | 85.2 | 9.5 | 8.6 | 1 |
| 38 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $10,665.96 | $28,503.68 | 85.2 | 9.5 | 8.6 | 1 |
| 39 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $11,230.72 | $29,068.44 | 85.2 | 9.5 | 8.6 | 1 |
| 40 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $11,795.49 | $29,633.20 | 85.2 | 9.5 | 8.6 | 1 |
| 41 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $12,360.25 | $30,197.97 | 85.2 | 9.5 | 8.6 | 1 |
| 42 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $12,925.02 | $30,762.73 | 85.2 | 9.5 | 8.6 | 1 |
| 43 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $13,489.78 | $31,327.49 | 85.2 | 9.5 | 8.6 | 1 |
| 44 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $14,054.54 | $31,892.26 | 85.2 | 9.5 | 8.6 | 1 |
| 45 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $14,619.31 | $32,457.02 | 85.2 | 9.5 | 8.6 | 1 |
| 46 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $15,184.07 | $33,021.79 | 85.2 | 9.5 | 8.6 | 1 |
| 47 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $15,748.83 | $33,586.55 | 85.2 | 9.5 | 8.6 | 1 |
| 48 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $16,313.60 | $34,151.31 | 85.2 | 9.5 | 8.6 | 1 |
| 49 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $16,878.36 | $34,716.08 | 85.2 | 9.5 | 8.6 | 1 |
| 50 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $17,443.12 | $35,280.84 | 85.2 | 9.5 | 8.6 | 1 |
| 51 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $18,007.89 | $35,845.60 | 85.2 | 9.5 | 8.6 | 1 |
| 52 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $18,572.65 | $36,410.37 | 85.2 | 9.5 | 8.6 | 1 |
| 53 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $19,137.42 | $36,975.13 | 85.2 | 9.5 | 8.6 | 1 |
| 54 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $19,702.18 | $37,539.89 | 85.2 | 9.5 | 8.6 | 1 |
| 55 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $20,266.94 | $38,104.66 | 85.2 | 9.5 | 8.6 | 1 |
| 56 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $20,831.71 | $38,669.42 | 85.2 | 9.5 | 8.6 | 1 |
| 57 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $21,396.47 | $39,234.19 | 85.2 | 9.5 | 8.6 | 1 |
| 58 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $21,961.23 | $39,798.95 | 85.2 | 9.5 | 8.6 | 1 |
| 59 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $22,526.00 | $40,363.71 | 85.2 | 9.5 | 8.6 | 1 |
| 60 | 6,000 | $15,000.00 | 6,122.45 | 122.45 | $6,600.00 | $134.69 | $6,734.69 | $1,500.00 | $900.00 | $764.76 | $1,391.67 | -$626.90 | $200.00 | $3,000.00 | $0.00 | $1,000.00 | $0.00 | $564.76 | $23,090.76 | $40,928.48 | 85.2 | 9.5 | 8.6 | 1 |
Complete your decision record
One machine-to-item contribution calculation, three financial thresholds, a stock/route/repair capacity check and opening funding tied to the same 60-month cash schedule. Enter the finding or number, the source and the next action for each row. “Supported” records your assessment of that item; it does not approve the business or certify completed research.
| Item and what to record | Your finding and evidence | Status and next action |
|---|---|---|
| Sites and installed scopeAccepted address, agreement, machine condition, delivery/payment configuration, access, power and exit terms | ||
| Successful sales and stockItem, net price, tax, opening/received/sold/lost/closing stock, refunds and out-of-stocks | ||
| Host and provider costsCommission denominator, fixed/percentage charges, cashless share, subscriptions and settlement dates | ||
| Paid resource clocksEvery visit, drive, preparation, incident, technical repair, management task and actual employer cost | ||
| Funding and next commitmentInstalled payments, inventory asset, deposit, training, supplier/settlement dates, deficit, buffer and verified funding |
5 items have no evidence recorded yet.
Entries are temporary and are not sent to us or saved automatically. Download your completed work before leaving or refreshing this page.
Choose your next action
| If your finding is… | Your next action |
|---|---|
| No positive item contribution | Revise supported price, product cost, loss and contract terms before assuming more vends. |
| Threshold is above the stock or paid-work ceiling | Revise the actual route, service scope, installed mix or funded staffing; do not prescribe undeliverable sales. |
| Cash is positive but EBIT is negative | Assess depreciation, asset life and a funded replacement plan before treating the cash as a return. |
| One machine is busier or access is narrower | Rebuild that machine’s item mix and service calendar, then recalculate the whole paid route. |
| Opening or settlement cash falls below retained funds | Fund the dated gap or change the commitment before spending. |
Errors that can change the result
- Using a seller placement or earnings promise as paid demand.
- Counting an authorization or refunded failed vend as another sale.
- Charging 2% acquired-item loss again as a percent of sales.
- Calling opening inventory both an immediate expense and a second cash deduction.
- Removing paid owner route, repair or management work.
- Treating positive mature cash as EBIT, asset replacement or opening payback.
Apply this to your business
These operating formats match the decisions in this guide.
Vending Machine Business
Owner-operated route of ten indoor packaged snack-and-drink combination machines at ten accepted third-party locations, with paid replacement work
Open the operating guide and state profiles →Use the same accepted sites, installed scope, item contribution, paid route and cash assumptions before committing to the equipment. Values entered here are not automatically transferred to another calculator.
Continue with the next part of your plan
- How to control vending locations, product stock and the complete paid route
A location-to-item control record that connects site rights, installed scope, stock, sales/refunds, tax, host/provider balances, route work, technical incidents and dated cash.
- How to compare equipment quotes and build the opening budget
A comparable two-quote cost calculation and a supplier commitment record.
- How to build a staffing roster before estimating payroll
A roster with complete task coverage and an annualized monthly staffing budget.
- Why a profitable business can still run out of cash
A profit-to-cash bridge and a clearly defined test for recovering the initial investment.
- How much startup financing do you need, and can you repay it?
A sources-and-uses brief, a net funding gap and a repayment scenario to discuss with a lender.
Sources and limits
The sources below provide the stated background. The worked examples, calculator defaults and decision exercises are authored teaching material. They do not establish market prices, local demand, legal applicability or completed state research.
- Vending Machine Business reference economics
Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
- Census: 2022 NAICS 445132 vending machine operators
Retail merchandise through machines the establishments service. The 2017 classification was 454210. A broad employer-establishment count is not ten-machine demand or a route income estimate.
- BLS May 2025 national occupation wage workbook
National cross-industry hourly medians for SOC 53-3031 driver/sales workers, 49-9091 coin/vending-machine repairers and 11-1021 general/operations managers are replacement-cost anchors, not vending employer quotes, contractor charges or complete employer costs.
- eVending: USI Futura 29-selection combination machine
Direct product offer, displayed machine configuration, nominal snack/drink capacity and stated parts-warranty scope. Freight, tax, accepted placement, installation, full labor and selected payment scope require a matched quote; it does not set the reference installed allowance.
- Nayax: VPOS Touch direct device offer
Direct hardware and required-plan offer; pricing depends on quantity/configuration and transaction arrangement. It does not establish the reference 6% blended payment allowance or require duplicate hardware on a machine already equipped.
- California CDTFA: applying and reporting vending-machine tax
California product-category taxable bases, tax-inclusive receipts and separate records. Applicability and rates must be resolved for the actual item and location; this is not a nationwide gross-to-net rule.
- Texas Comptroller: Rule 3.293 food and vending sales
Subsection (d), category-specific treatment of vending food, candy, soft drinks and water and tax-inclusive notice. It does not set another jurisdiction’s tax or the reference net price.
- IRS: business recordkeeping
Keeping supporting business records.
Source background and its scope are stated above. The guide update date does not change a source observation period. Research and review standards · Report an issue
When you need a longer financial plan
Use a financial model to organize a broader forecast after defining your own operating assumptions. The site’s research, your worksheet entries and any purchased workbook are separate; entries are not transferred automatically.
Continue with the published financial scenario