How to control vending locations, product stock and the complete paid route
Operate a vending route from one location-and-machine register tied to accepted terms, usable product stock, successful paid item-vends and the complete paid service calendar. The reference has ten machines at ten sites and 60 monthly stops. A good location description, nominal product capacity or a working card reader does not establish retained sales, stock availability or a feasible route.
What you will produce: A location-to-item control record that connects site rights, installed scope, stock, sales/refunds, tax, host/provider balances, route work, technical incidents and dated cash.
Updated October 20, 2026 · Worked examples and editable worksheets
What to have ready
Bring accepted placement agreements, machine serial/configuration records, installed quotes, product batch/cost records, sales and settlement exports, host statements, route/repair logs and the actual official requirements for every jurisdiction.
Work through the calculation and decision
Establish an accepted location before ordering its machine
Give each location a stable identifier and record the host, exact address, written acceptance, placement term, permitted products, exclusivity, operating/access windows, power/network responsibility, physical footprint and customer access. Record commission basis and timing, site security, damage responsibility, renewal, termination, removal and redeployment costs. Do not turn an unaccepted lead into an installed revenue location.
Link the accepted site to a specific machine and its serial number, condition, dimensions, service access, delivery path, installation, anchoring and accepted payment configuration. Obtain the relevant authority and host decisions for that address. A single approval or contract does not automatically cover the other nine sites or a different product format.
Census: 2022 NAICS 445132 vending machine operators · 2022 industry definition · Checked 2026-10-20
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Compare the complete machine and payment configuration
A direct manufacturer page can establish a particular machine’s displayed price, selections, nominal snack/drink capacity and stated warranty scope. It does not price an accepted host agreement, freight, tax, difficult access, electrical work, installation, full warranty labor or every payment option. The reference’s $6,500 installed payment-ready allowance per machine remains an assumption to replace with a matched quote.
The direct payment-device offer separates hardware from its required monthly plan, while transaction pricing depends on the selected arrangement. Confirm whether a machine already includes compatible payment hardware before adding another device. Record hardware ownership, activation, subscriptions, processing, connectivity, settlement, refunds, minimums, cancellation and responsibility during an outage. The reference’s 6% payment allowance is not a provider quote.
eVending: USI Futura 29-selection combination machine · Offer checked October 20, 2026 · Checked 2026-10-20
Nayax: VPOS Touch direct device offer · Offer checked October 20, 2026 · Checked 2026-10-20
Keep item cost, stock loss and customer refunds distinct
For each machine and product, record item identifier, pack/unit conversion, supplier, received quantity, acquisition cost, batch/date, shelf life, storage conditions, loaded quantity, successful paid sales, free replacements, returns, waste/loss and closing quantity. Reconcile beginning stock + receipts − successfully supplied items − other documented removals to ending stock. Mixed packs and partial cases must use consistent whole-item units.
A customer refund can reduce realized revenue while the supplied or lost item still consumes stock. A failed authorization without supply is not a paid item sale. Separate product spoilage/shrink from machine downtime and technical incidents; each affects another part of the plan. The reference’s 2% acquired-item loss is an assumed cost/stock rate, not observed shrink at a host site.
IRS: business recordkeeping · Keeping supporting business records.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Schedule the busiest selection and the longest actual service gap
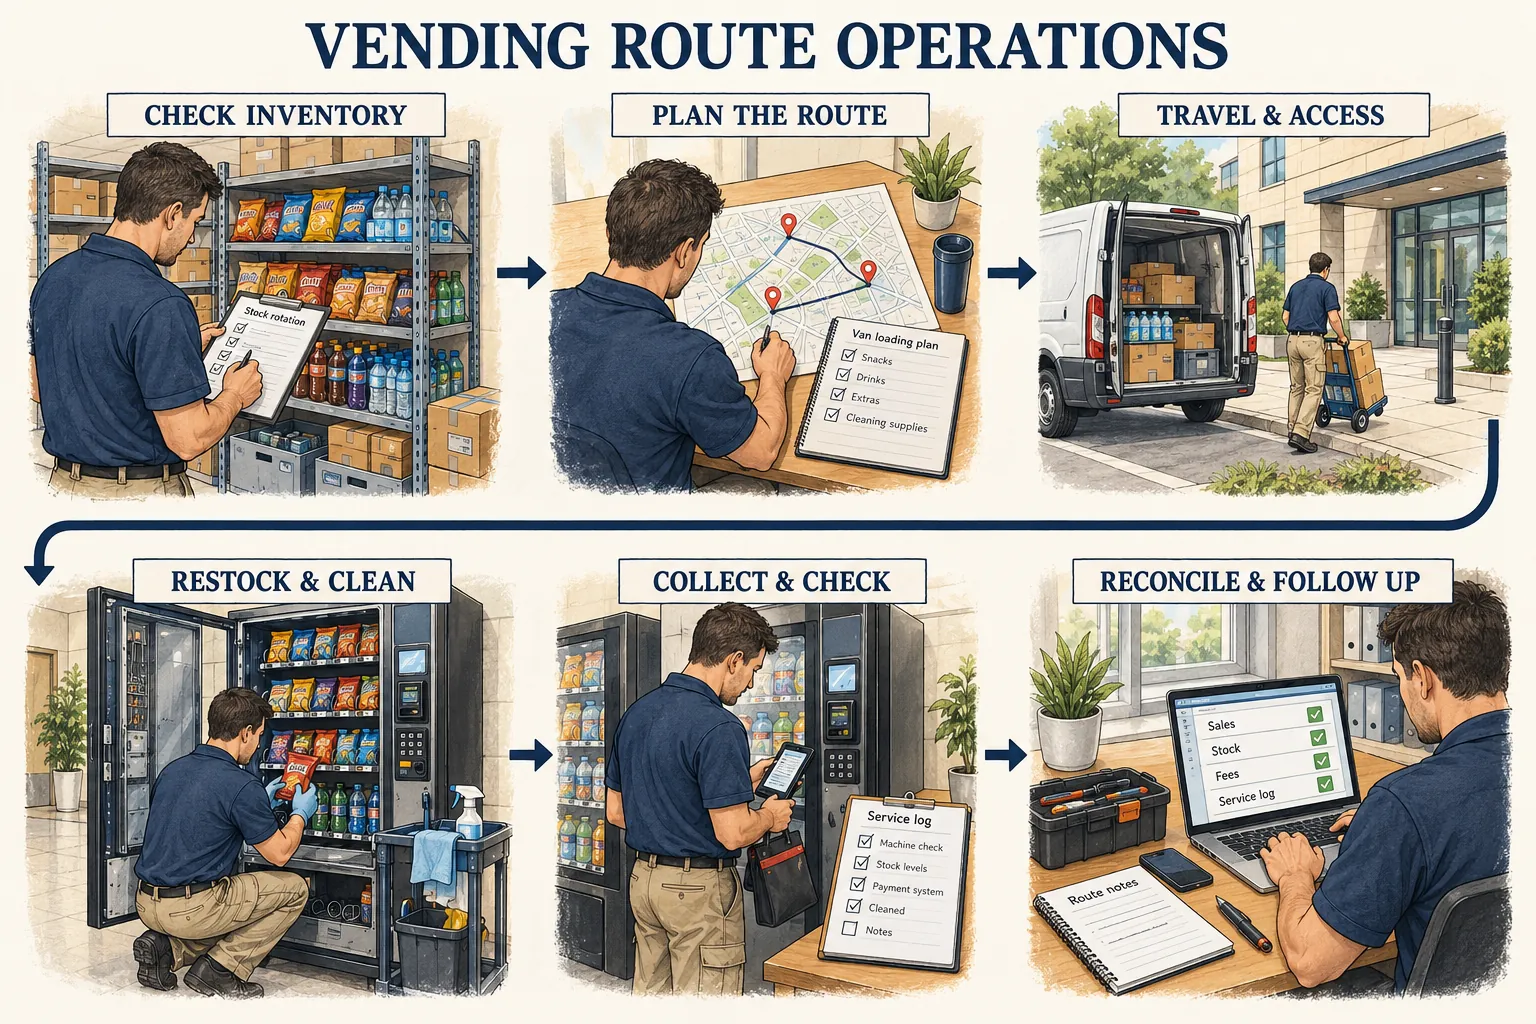
The teaching route has six visits per machine per month and a maximum five-day gap on a recurring calendar. Ten sites therefore create 60 stops before extra incidents. Count warehouse loading, the drive/access allocation, cleaning, product rotation, replenishment, price checks, cash/settlement reconciliation and departure. An average stop count does not prove that all hosts admit the operator at the needed times.
The 180 usable stocked positions are a conservative authored working inventory, not the manufacturer’s nominal capacity or a guarantee that every selection stays in stock. Use product-specific sales and positions at the busiest machine. Equal route-average sales can conceal an empty popular drink, inaccessible machine or fault at one site. Replan the sequence and paid hours when a selection, expiry date, host restriction, vehicle load or recovery trip binds.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
eVending: USI Futura 29-selection combination machine · Offer checked October 20, 2026 · Checked 2026-10-20
Assign complete incidents to paid route and technical clocks
Record the machine, product/payment event, customer outcome, equipment condition, original cause, triage, refund or replacement, travel, access, repair/materials, responsible person and return-to-service check. Link the event to its original sale and stock record. An included recovery visit is paid work without another product sale; closing a ticket does not by itself prove reliable dispensing.
The reference separately pays driver/sales, technical repair and management work. At its 8,000-vend ceiling, expected route recovery and technical incidents are recomputed at that activity; repair uses all 12 paid hours. The route allowance includes customer triage, access, collection and incident driving; technical time adds diagnosis/repair without counting that driving again. Events may overlap, while the same work is counted once. The role clocks are assumptions anchored to occupation wages, not a promise of qualified after-hours response. Obtain the actual provider, parts/labor warranty and response arrangement rather than treating a parts warranty as free complete repair.
BLS May 2025 national occupation wage workbook · May 2025
eVending: USI Futura 29-selection combination machine · Offer checked October 20, 2026 · Checked 2026-10-20
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
Classify tax and food scope by product and jurisdiction
California CDTFA vending guidance distinguishes cold-food and beverage categories and explains tax-inclusive receipts and separate records. Texas Rule 3.293 distinguishes food, candy, soft drinks and water in its vending treatment. These official examples demonstrate why one gross-to-net percentage cannot safely be copied across all products and locations. Determine the actual taxable base, rate, included tax and records before using a displayed consumer price as net revenue.
Ohio Revised Code 3717.42(B)(9) exempts a location offering only prepackaged foods that are not potentially hazardous from the stated food-service licensing requirement; subsection (B)(10) separately addresses a qualifying servicing place. That scope does not exempt a different food format or settle sales-tax registration. Section 5739.17 provides a separate vendor-license framework for taxable retail activity. Verify the exact accepted product/servicing scope and current responsible authority; a food-service exemption is not a universal business approval.
California CDTFA: applying and reporting vending-machine tax · Guidance checked October 20, 2026 · Checked 2026-10-20
Texas Comptroller: Rule 3.293 food and vending sales · Rule text checked October 20, 2026 · Checked 2026-10-20
Ohio Revised Code Section 3717.42 · Effective October 3, 2023; checked October 20, 2026 · Checked 2026-10-20
Ohio Revised Code Section 5739.17 · Effective April 9, 2025; checked October 20, 2026 · Checked 2026-10-20
Reconcile the host and provider to the actual cash ledger
Connect successful item sales and refunds to cash collected, card settlement, fees, receivables, host commission, tax liabilities and differences. Preserve the contractual denominator: a commission on gross receipts does not equal the reference percentage of net sales. Keep hardware/subscriptions, variable charges, reserves/holds and refunds visible so a low advertised processing figure does not conceal a different total cost.
Inventory purchases use cash before sale; sold-product cost and loss are expenses under the stated earning policy. The reference funds $3,000 stock at opening and keeps that cost balance unchanged through replacements, while a two-day net-sales receivable models settlement. Actual supplier credit, bulk stock builds, seasonal inventory, cash collection delays, host remittance and tax dates need dated adjustments. Restricted tax and refundable customer money do not become available owner cash.
Nayax: VPOS Touch direct device offer · Offer checked October 20, 2026 · Checked 2026-10-20
California CDTFA: applying and reporting vending-machine tax · Guidance checked October 20, 2026 · Checked 2026-10-20
Texas Comptroller: Rule 3.293 food and vending sales · Rule text checked October 20, 2026 · Checked 2026-10-20
IRS: business recordkeeping · Keeping supporting business records.
Decide to retain, revise, remove or add a location
Review a complete paid test cycle by site: accepted scope, successful net sales, product cost/loss, host/provider charges, product availability, every stop and recovery hour, technical reliability and collected contribution. Include incremental removal/redeployment and the share of standing work when comparing a marginal site. Do not use a portfolio average to hide a machine that repeatedly consumes stock or service without adequate contribution.
Before another machine commitment, confirm the next accepted location and installed quote, item demand evidence, matched host/provider terms, supported service calendar and funded dated cash. A route acquisition, fresh-food operation or micro-market has different obligations and needs its own evidence/model. Use the single route calculator to update contribution, all paid clocks and opening funding from the revised plan.
Vending Machine Business reference economics · Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
One machine ties five records to one replenishment cycle
This qualitative example invents no local demand, signed site, achieved price, permit fee or response time.
| Connected record | What to establish | Decision it supports |
|---|---|---|
| Accepted site / machine | Address, host agreement, installed serial/configuration, access, power and exit terms | The right equipment belongs at an accepted usable location |
| Product stock | Beginning/received/loaded/sold/lost/closing items, cost, batch and shelf life | Fund the right inventory and address a stockout or loss |
| Successful earning | Paid supplied item, tax, refund, net price and matched receipt | Separate sale, authorization, failed dispense and replacement |
| Paid route / incident | Preparation, stop, drive, access, service, cause, repair and closure | The next service cycle fits funded complete work |
| Host / provider / cash | Commission basis, provider charges, settlement, tax and supplier dates | Retained collected contribution and the next cash commitment |
What this changes: The site, item ledger, successful sale, complete paid work and settled money must describe the same operating event. Machine presence or a payment authorization alone does not establish contribution.
Illustrative amounts are rounded for display. Use the full inputs and stated units when recalculating; an approximate threshold is not itself a sufficient activity prescription.
Reference route and stock boundary
| Item | Authored reference | Selected-route check |
|---|---|---|
| Accepted physical supply | 10 machines / 10 indoor sites | Written acceptance, condition, footprint, access and installation |
| Sales / replenishment | 6,000 paid vends; 60 stops monthly | Actual paid item mix and a calendar maintaining the five-day gap |
| Usable stocked positions | 180 per machine before expected 2% acquired-item loss | Selection-specific capacity, shelf life and observed demand |
| Paid coverage | 104 route / 12 repair / 17.33 management hours | Every duty, qualification, incident, travel and employer cost |
| Complete monthly ceiling | 8,000 paid item-vends | Conditional equal-machine sales; technical repair binds |
These are disclosed control assumptions. They do not establish a signed site, local sales, a guaranteed service interval, a complete installation quote or a completed state feasibility study.
Complete your decision record
A location-to-item control record that connects site rights, installed scope, stock, sales/refunds, tax, host/provider balances, route work, technical incidents and dated cash. Enter the finding or number, the source and the next action for each row. “Supported” records your assessment of that item; it does not approve the business or certify completed research.
| Item and what to record | Your finding and evidence | Status and next action |
|---|---|---|
| Location and equipmentAccepted address, agreement/exit, serial/configuration, usable positions, installed quote and service access | ||
| Item and stockWhole-item conversions, cost, batch/shelf life, opening/receipt/sale/loss/closing reconciliation | ||
| Earning and taxSuccessful paid item, refund, gross price, taxable category, tax and net revenue | ||
| Route and incidentEvery duty and drive, access window, longest gap, fault, response, paid time, materials and closure | ||
| Host/provider and cashExact cost basis, subscriptions/fees, receipts/settlement, commission, tax, suppliers and unrestricted cash | ||
| Next commitmentRetain/revise/remove/add, evidence, funded workload, installed amount and cash date |
6 items have no evidence recorded yet.
Entries are temporary and are not sent to us or saved automatically. Download your completed work before leaving or refreshing this page.
Choose your next action
| If your finding is… | Your next action |
|---|---|
| Placement or installation scope is unresolved | Resolve the actual host, address and full installed configuration before equipment spending. |
| Popular selections empty before the next visit | Rebalance stock and the actual route calendar; include the extra paid time before increasing assumed sales. |
| Faults or refunds recur | Track original cause, paid recovery and net item contribution; repair, restrict or replace supported scope. |
| Tax or commission denominator differs | Rebuild gross-to-net and retained contribution from the actual product and contract. |
| A site does not support its full obligations | Test a scoped price/mix/visit change, or plan funded removal/redeployment before another placement. |
Errors that can change the result
- Equating ten machines ordered with ten accepted income-producing sites.
- Adding payment hardware already included in the quoted configuration.
- Using nominal capacity as wanted-product availability.
- Removing repair travel, warranty labor or paid owner work.
- Applying another jurisdiction’s tax or food exemption to the whole route.
- Treating a portfolio sales average as evidence for every location.
Apply this to your business
These operating formats match the decisions in this guide.
Vending Machine Business
Owner-operated route of ten indoor packaged snack-and-drink combination machines at ten accepted third-party locations, with paid replacement work
Open the operating guide and state profiles →Use the installed location, product contribution, service schedule and cash dates to decide whether another machine belongs on the route. Values entered here are not automatically transferred to another calculator.
Continue with the next part of your plan
- Can vending sales cover stock, the paid route and machine investment?
One machine-to-item contribution calculation, three financial thresholds, a stock/route/repair capacity check and opening funding tied to the same 60-month cash schedule.
- How to compare equipment quotes and build the opening budget
A comparable two-quote cost calculation and a supplier commitment record.
- How to find the permits and approvals your business actually needs
An approval register with official responses and the next unresolved question.
- How to build a staffing roster before estimating payroll
A roster with complete task coverage and an annualized monthly staffing budget.
- Why a profitable business can still run out of cash
A profit-to-cash bridge and a clearly defined test for recovering the initial investment.
Sources and limits
The sources below provide the stated background. The worked examples, calculator defaults and decision exercises are authored teaching material. They do not establish market prices, local demand, legal applicability or completed state research.
- Vending Machine Business reference economics
Authored ten-machine packaged snack/drink route, paid work, stock, financial boundaries and cash; not observed sales, site acceptance or installed quotes.
- Census: 2022 NAICS 445132 vending machine operators
Retail merchandise through machines the establishments service. The 2017 classification was 454210. A broad employer-establishment count is not ten-machine demand or a route income estimate.
- eVending: USI Futura 29-selection combination machine
Direct product offer, displayed machine configuration, nominal snack/drink capacity and stated parts-warranty scope. Freight, tax, accepted placement, installation, full labor and selected payment scope require a matched quote; it does not set the reference installed allowance.
- Nayax: VPOS Touch direct device offer
Direct hardware and required-plan offer; pricing depends on quantity/configuration and transaction arrangement. It does not establish the reference 6% blended payment allowance or require duplicate hardware on a machine already equipped.
- California CDTFA: applying and reporting vending-machine tax
California product-category taxable bases, tax-inclusive receipts and separate records. Applicability and rates must be resolved for the actual item and location; this is not a nationwide gross-to-net rule.
- Texas Comptroller: Rule 3.293 food and vending sales
Subsection (d), category-specific treatment of vending food, candy, soft drinks and water and tax-inclusive notice. It does not set another jurisdiction’s tax or the reference net price.
- Ohio Revised Code Section 3717.42
Subsections (B)(9) and (B)(10), stated food-service licensing exemptions for qualifying prepackaged non-potentially-hazardous foods and servicing scope; not an exemption for every product or all business/tax duties.
- Ohio Revised Code Section 5739.17
Vendor licensing for the applicable taxable retail activity. Determine actual activity and jurisdiction; a separate food-service exemption does not settle sales-tax registration.
- BLS May 2025 national occupation wage workbook
National cross-industry hourly medians for SOC 53-3031 driver/sales workers, 49-9091 coin/vending-machine repairers and 11-1021 general/operations managers are replacement-cost anchors, not vending employer quotes, contractor charges or complete employer costs.
- IRS: business recordkeeping
Keeping supporting business records.
Source background and its scope are stated above. The guide update date does not change a source observation period. Research and review standards · Report an issue
When you need a longer financial plan
Use a financial model to organize a broader forecast after defining your own operating assumptions. The site’s research, your worksheet entries and any purchased workbook are separate; entries are not transferred automatically.
Continue with the published financial scenario