How many clients can your salon or detailing business serve?
Calculate paid service capacity, allow for cancellations, and compare completed appointments with operating cash break-even.
Work through the guide →
Define the vehicle condition and included package, time both technicians' work and verify the fixed site's water-handling route before committing. The stated national wage scenario uses 3.2 completed jobs per trading day at $240.00 per completed detailing job, producing $4,462 mature monthly EBIT and $58,177 modeled opening funding. Sales, capacity and nonwage costs remain planning assumptions.

A package earns its contribution only when intake, cleaning, drying, quality checks and handover fit the paid team and occupied space. A larger vehicle or difficult condition can increase time without increasing the collected price.
One completed package is one job. Daily fractional counts are operating averages across trading days, not permission to schedule part of a vehicle as a completed job.
At the assumed activity, the mature month produces $4,812 EBITDA, $4,462 EBIT and $4,612 cash after maintenance. The first twelve modeled months generate $30,512 of operating cash; they do not represent a full year at the mature run rate.
The EBIT threshold is approximately 2.24 completed jobs per trading day; it uses the same price, variable-cost basis and complete paid roster. The listed ceiling is 4 completed jobs per trading day, with the operating qualifications in the capacity explanation below. Reconcile technician person-hours and elapsed bay occupation separately. Allow for intake, drying, cleanup, rework and delayed customer collection before accepting the next whole vehicle.
| Test | Entered activity or cost | Monthly EBIT |
|---|---|---|
| Published reference | 3.2 completed jobs per trading day | $4,462 |
| 20% less earned activity | 2.56 completed jobs per trading day | $1,488 |
| 10% higher wage benchmarks | 1.10 × the same occupational wage anchors | $3,746 |
| 20% higher occupancy cost | $1,920.00 monthly occupancy | $4,142 |
Of the three separate tests shown, 20% less earned activity makes the largest change to monthly EBIT: -$2,974. This is a result of the stated test sizes, not a probability or a universal risk ranking.
The two paid technicians include lead and nonservice duties. A two-person job lasting ninety minutes uses three labor-hours, while the bay is occupied for the elapsed time.
Opening payments of $31,676, the deepest cumulative operating cash deficit of $6,388 in month 2, and the retained buffer of $20,113 add to $58,177 modeled funding. Refundable deposits are included in opening cash uses; they are not operating expenses. Funding is a scenario total, not a quote or a financing recommendation.
This is a fixed-site retail package with prompt collection. A fleet-credit or mobile-travel operation would change receivables, paid time, vehicles and the cash schedule.
EBITDA pays the full modeled roster and operating costs. EBIT also deducts depreciation. Mature cash deducts maintenance investment from EBITDA, after receivables stop growing. All three exclude financing, income taxes and additional owner distributions.
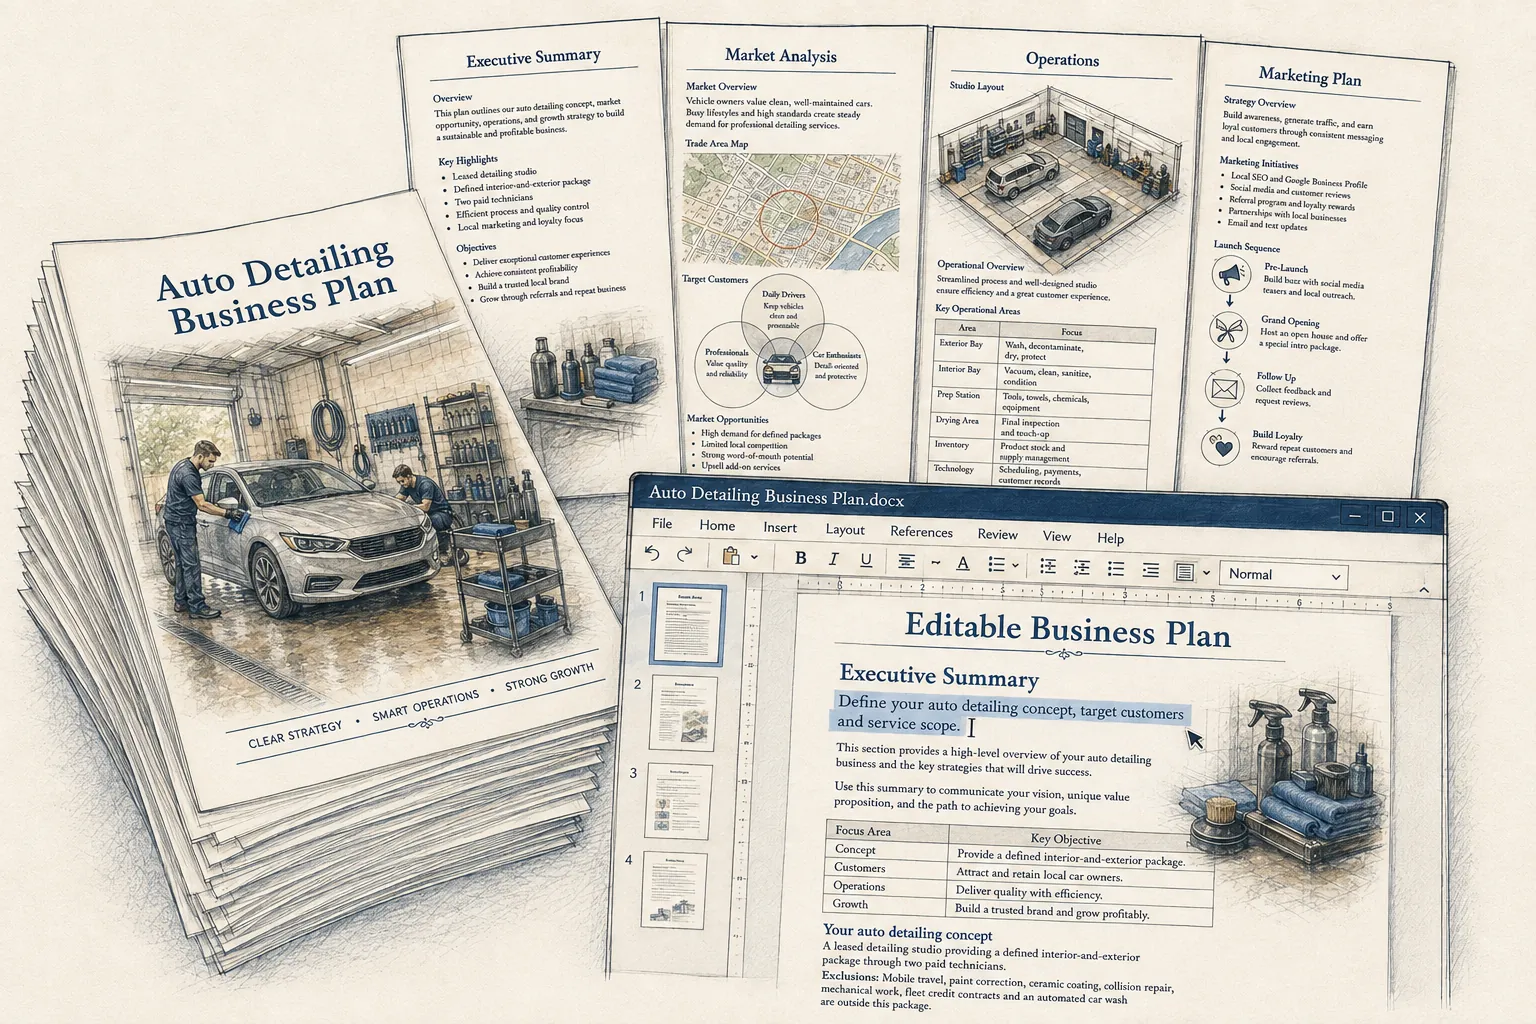
If normal condition variation pushes the package beyond its paid time or available space, change the condition boundaries, price or site before expanding bookings. Time representative vehicle conditions under a written package, log consumables and rework, and obtain a premises and wastewater answer for the selected address.
The wage observation is the BLS May 2025 national occupational median for each stated role. Hours, employer allowance, sales, prices, capacity and all nonwage costs are authored assumptions. Read the calculation definitions.
Calculations retain the exact input values. USD totals are displayed to whole dollars and blended prices to cents; activity and threshold estimates are displayed to up to two decimals. Rounded thresholds are estimates, not prescriptions for a sufficient whole job, visit or member count.
A completed paid detailing job is the reference unit. Vehicle size, initial condition and included tasks can change job duration and consumables. A single advertised starting price is a weak estimate of the realized ticket.
Maintenance appointments and repeat clients can support demand, but an occasional deep clean does not become monthly recurring revenue without evidence. Separate repeat retail jobs from fleet agreements and their payment terms.
| Format | What changes | How to use it |
|---|---|---|
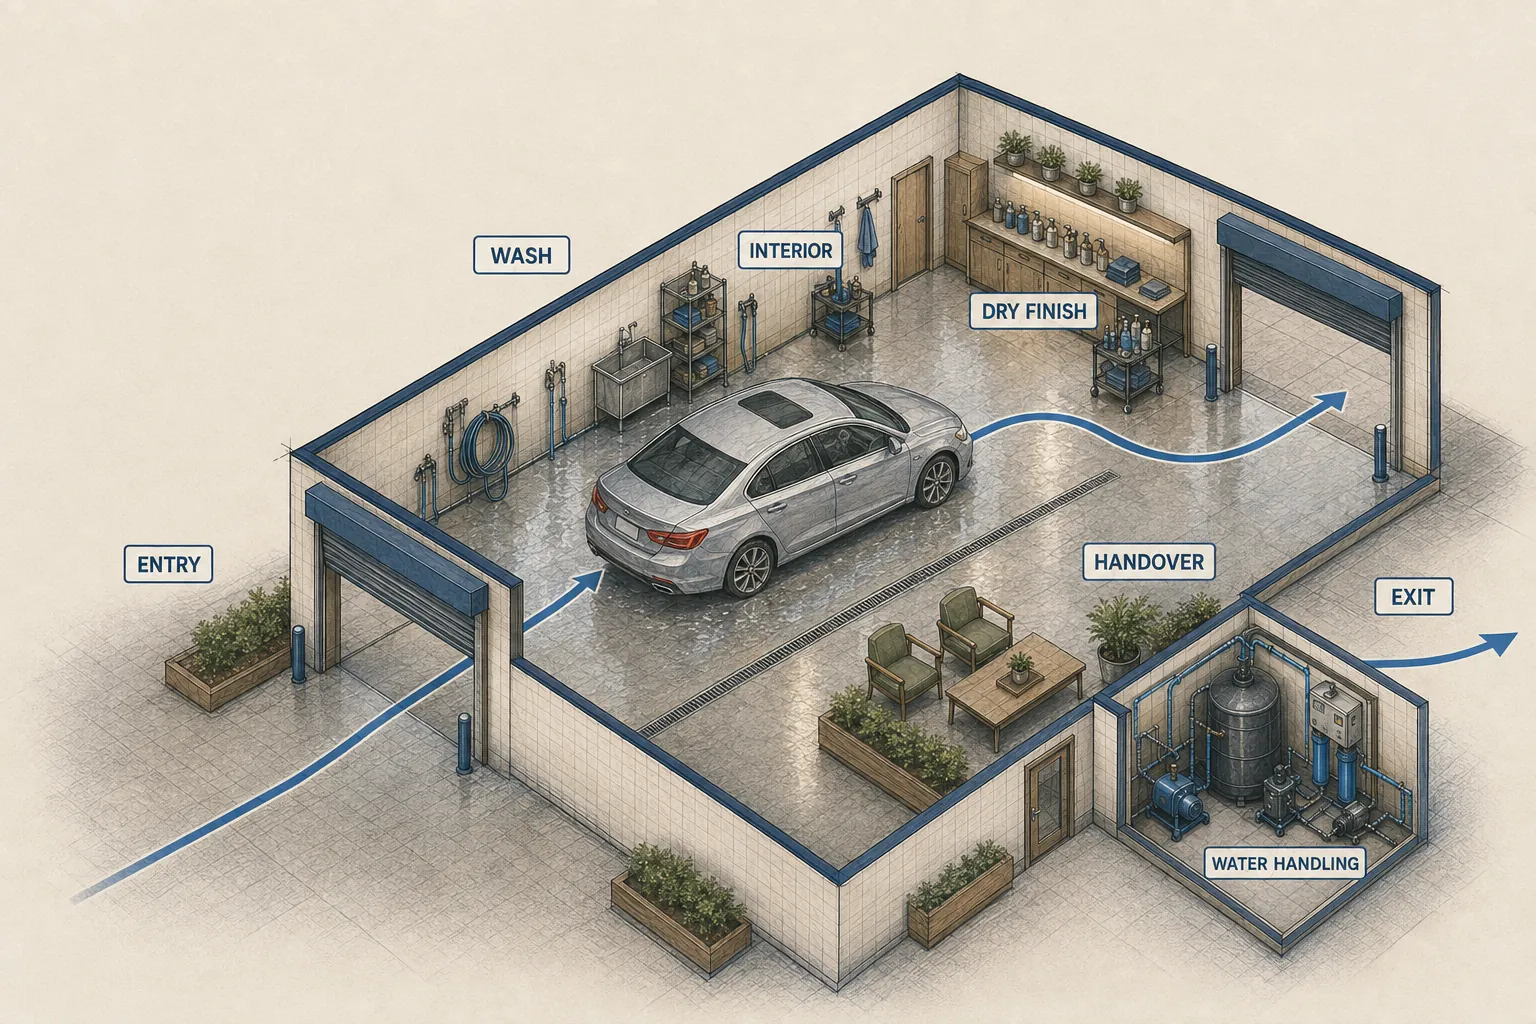
| Fixed-site detailing studio | Customers bring vehicles to a dedicated work location | The reference here uses two paid technicians and a limited package menu. |
| Mobile detailing | The team and equipment travel to the customer | Travel, vehicle costs, weather, water access and site permissions require a different model. |
| Specialist correction or coatings | Longer jobs and more specialized procedures | Service duration, training, scope and liability differ from routine detailing. |
A founder who likes process quality, physical service work and detailed customer intake. A studio also requires appointment management and careful control of work that varies with vehicle condition.
The figures below are a national wage reference scenario. The paid roster uses May 2025 BLS national occupational medians. Prices, customer volume, rent, equipment and other commercial inputs are authored assumptions. This is not a researched average startup cost, owner-income promise or a funding recommendation.
| Input or result | Reference | What to verify |
|---|---|---|
| Completed sales units | 70.4 jobs / month | 3.2 completed jobs per trading day; demand requires evidence. |
| Net selling price | $240.00 | Build and test a relevant local menu, package or contract scope. |
| Revenue | $16,896 | Calculated volume × price, not observed sales. |
| Paid payroll | $7,157 / month | National wage medians × the stated hours × the 18% employer allowance. |
| Opening payments | $31,676 | Authored equipment and setup allowances, deposit and paid training. |
| Funding including reserve | $58,177 | Opening payments + deepest modeled operating deficit + retained buffer. |
| Mature operating profit (EBIT) | $4,462 / month | After the full paid roster and depreciation; before financing and income taxes. |
| Approximate EBIT threshold | Approximately 2.2 completed jobs per trading day | A rounded estimate. Test whole permitted activity against the full roster and resource constraints. |
Two technicians × 8 paid hours × 75% productive time ÷ 3 labor hours per job = 4 jobs per day. A two-person job lasting 90 minutes uses 3 labor hours. The monthly ceiling is 88 jobs across 22 trading days; quoting, cleanup, breaks and lead duties consume the remaining paid time.
8% chemicals, towels and job consumables plus 4% payment processing and variable disposal costs; labor is separate. Utilities $350; insurance $350; marketing $350; booking, communications and administration $250 per month.
Cleaners of Vehicles and Equipment is a broad wage proxy. It includes work outside professional car detailing and does not establish a specialist rate. Lead duties remain within the two-technician paid roster.
BLS May 2025 national wage workbook · Calculation definitions · How owner income differs from EBIT
| Workstream | What the brief needs | Decision before spending |
|---|---|---|
| Site and water handling | Bay access, drainage, power, lighting and a confirmed wastewater route | Resolve site suitability before fit-out or accepting bookings. |
| Service tools | Vacuuming, extraction, wash tools, drying, chemicals and PPE | Choose equipment for the actual packages rather than an unlimited service menu. |
| Intake and scheduling | Condition records, customer sign-off, booking and handover procedure | Allocate time for inspection and communication, not just cleaning. |
Compare installed scope, exclusions and payment dates. Do not treat an unquoted item as zero or count a bundled installation twice. How to compare equipment quotes and build the opening budget explains a reusable quote ledger.
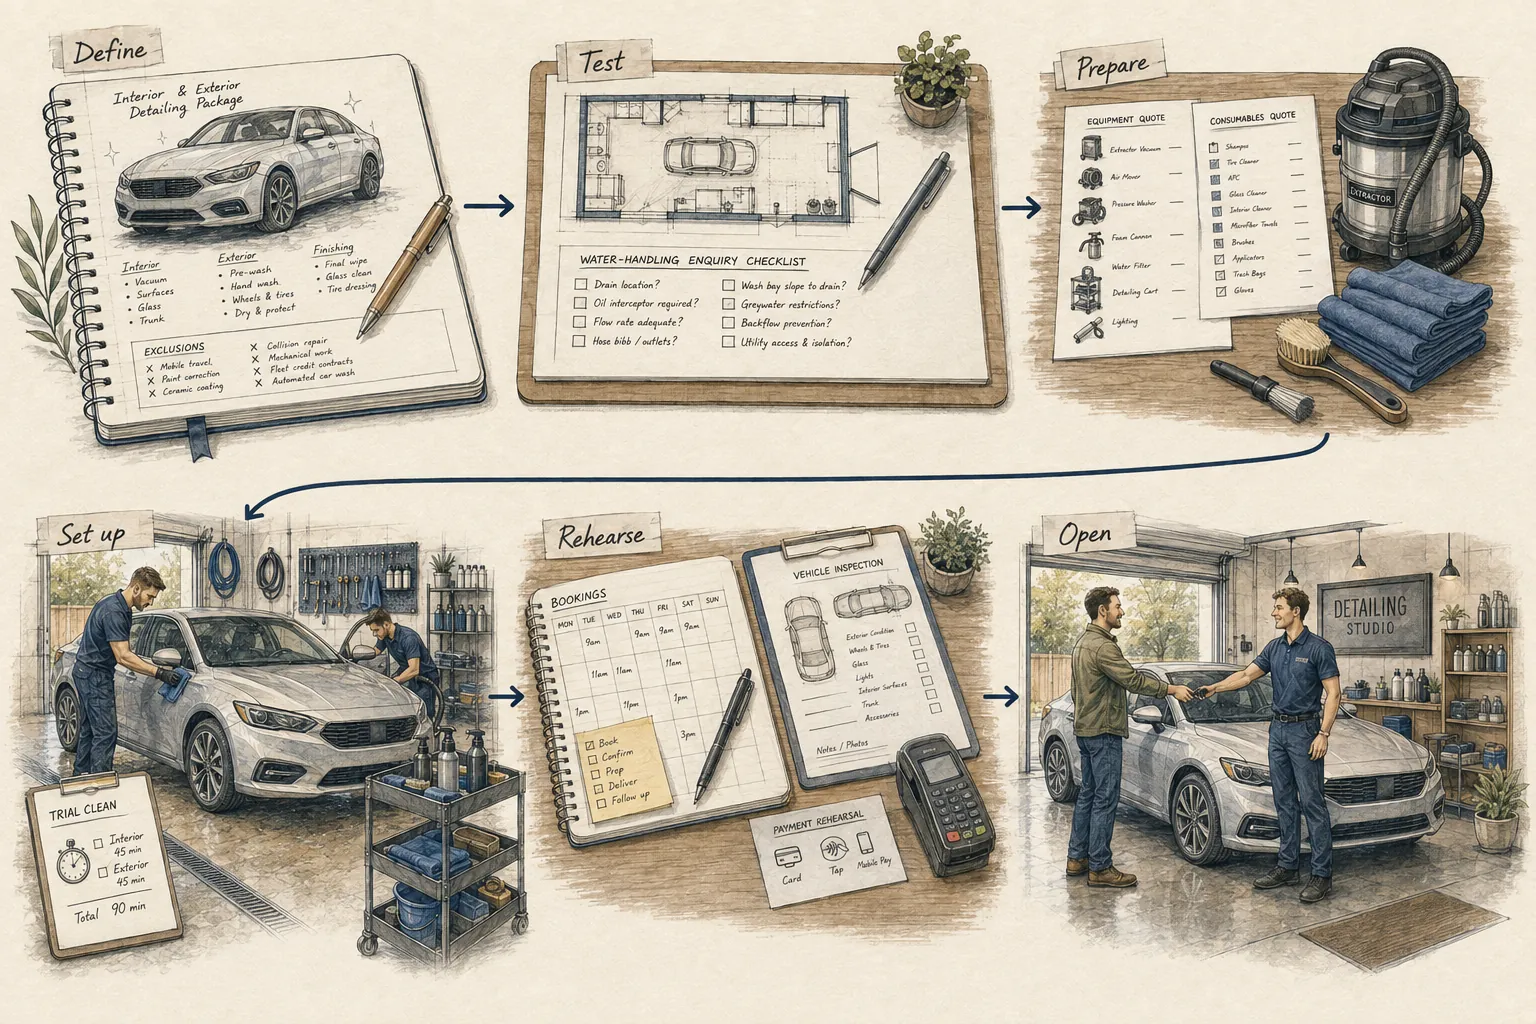
Record the included tasks and condition limits. Measure both elapsed bay time and total technician-hours; two people working for 90 minutes consume three labor-hours.
Ask the relevant local and state offices about the proposed use, water supply, wastewater collection or discharge, chemicals and waste. A usable garage is not evidence that the detailing operation is approved.
Build the package from paid labor, consumables and a contribution to fixed costs. State how unusually dirty vehicles, larger vehicles and additional tasks change the quote.
Test booking, vehicle inspection, keys, quality checks, drying and collection. Record rework and customer wait time before increasing the daily booking ceiling.
| Measure | Why it changes a decision |
|---|---|
| Technician-hours per completed job | Tests whether the package actually matches the roster. |
| Bay occupation and gaps | Identifies a space bottleneck or unfilled appointments. |
| Realized ticket by package and condition | Shows whether additional work is priced or absorbed. |
| Callbacks and consumables per job | Reveals contribution lost after the initial handover. |
Review actuals against the scope you priced. If an extra service, new trading hour or more distant client changes the work, update the roster and contribution calculation before expanding.
Describe fixed-site or mobile operation, vehicle volume, water use, discharge or collection method, chemical storage and waste. Identify the responsible planning, utility and environmental offices for the actual site; do not assume runoff is an acceptable disposal route.
Each state profile links to official registration, tax and employer routes, together with the questions still requiring an address-specific answer. How to find the permits and approvals your business actually needs provides the record to keep.
Counting a two-person job as only one person’s time, ignoring wastewater suitability, or booking more vehicles than the bay can turn around can overstate the service capacity before the first month.
Write a response that changes the actual cause: narrower scope, a different site, revised paid staffing, a tested price or a delayed opening. A larger cash buffer only addresses a temporary timing gap.
Calculate paid service capacity, allow for cancellations, and compare completed appointments with operating cash break-even.
Work through the guide →Compare equipment at installed usable scope, account for excluded costs and connect supplier payment terms to the opening cash plan.
Work through the guide →Calculate contribution, the price required at realistic sales volume and the number of completed services needed to cover fixed costs.
Work through the guide →Build an activity-and-address approval register with the responsible office, exact question, response, dependencies and renewal dates.
Work through the guide →Restaurant trade is organized around meal periods and a food-service team. A detailing studio is organized around vehicle packages, technician-hours and available bays. The second format’s smaller number of daily jobs makes job scope and duration especially consequential.
Compare the operating choices →A coffee shop serves many short transactions; a detailing studio serves fewer jobs that occupy technicians and space for longer. The practical choice depends on whether you can establish a buying location or a reliable package-and-booking operation.
Compare the operating choices →Both businesses sell a defined cleaning result, but their units and operating constraints differ. Recurring commercial cleaning depends on route density and repeated account scope; a detailing studio depends on vehicle condition, technician-hours and usable bay time.
Compare the operating choices →Both are appointment-led service businesses in these reference formats. A salon sells skilled practitioner time to a person; a detailing studio sells technician work and space use for a vehicle. Service mix, completion rates and exceptions matter more than the headline ticket.
Compare the operating choices →A detailing studio uses technician-hours and bay time to complete individual vehicles. A laundromat lets customers operate machines, but depends on a larger machine bank, utility envelope and continuous availability.
Compare the operating choices →A detailing studio completes individually scoped vehicle jobs through technician and bay time. A daycare center delivers repeated full-day supervision through age-group rooms and qualified paid coverage.
Compare the operating choices →Both businesses complete condition-sensitive jobs through skilled labor and fitted resources. Detailing manages vehicles and bay occupation; pet grooming adds live-animal handling, controlled handoff and sequential bathing, drying and table work.
Compare the operating choices →Both formats use paid field or technical labor and equipment to complete condition-sensitive work. The detailing studio brings vehicles to fixed bays; the landscaping company moves two crew-and-equipment systems among residential properties.
Compare the operating choices →An Auto Detailing Business brings condition-sensitive vehicles to fixed bays for longer technical jobs. A Food Truck brings a prepared menu to approved locations for many shorter orders. Both depend on water, equipment uptime and paid workflow, but their service units and site routes differ.
Compare the operating choices →An Auto Detailing Business completes fewer, longer technical jobs whose scope changes with vehicle condition. A Bakery completes many retail orders supported by whole batches and perishable inventory. Both use fitted wet-service premises, paid labor and equipment, but their flow and waste risks differ.
Compare the operating choices →An Auto Detailing Business earns from condition-sensitive vehicle jobs in fixed bays. A Fitness Studio earns recurring member-months through a shared room and scheduled instructors. Both use a fitted premises, but vehicle dwell time and repeated member access require different capacity records.
Compare the operating choices →An Auto Detailing Business completes scoped vehicle packages through technician and bay capacity. An HVAC Company completes diagnostic, repair, and replacement work through technician, vehicle, route, parts, and authorization capacity. Both require strong intake and quality control, but HVAC jobs occur on customer systems and can create larger supplier and callback exposure.
Compare the operating choices →An Auto Detailing Business completes scoped vehicle packages through technician and bay capacity at one site. A Moving Company transports customer property between addresses through one crew and truck. Both need careful intake and condition records, but moving adds route, building access, custody, weight, loading, and household-goods claim exposure.
Compare the operating choices →Both businesses receive customer vehicles at a fixed site. Auto Detailing earns from completed cleaning and appearance packages through technician and work-bay time. Auto Repair earns from diagnosis, sold labor operations, and parts. Repair generally adds deeper technical scope, customer authorization, equipment, parts cash, safety-critical work, and warranty exposure.
Compare the operating choices →An Auto Detailing Business earns from completed detailing packages through technician hours, bays, water, tools, and vehicle handoff. A Plumbing Company earns from completed and collected residential service jobs through licensed plumbers, two vehicles, dispatch, materials, permits, and callback control. Both must fit paid capacity to realized contribution, while plumbing adds address-to-address travel, trade authority, water and gas system risk, material acquisition, and return-service exposure.
Compare the operating choices →An Auto Detailing Business earns from completed detailing packages through technician hours, bays, water, tools, and vehicle handoff. An Electrical Contractor earns from completed and collected residential service and small-alteration jobs through licensed electricians, two vehicles, dispatch, sold hours, materials, permits, inspections, testing, and rework control. Both must fit paid capacity to realized contribution, while electrical adds address-to-address travel, trade authority, code and energized-work risk, material compatibility, inspection dependencies, and return-service exposure.
Compare the operating choices →Auto Detailing Business earns from completed detailing packages and is constrained by technician hours, bays, water, tools, and vehicle handoff. Pest Control Company earns a monthly household-plan yield while delivering a separate calendar of inspections, initial visits and callbacks. Compare realized contribution and paid capacity in their own units; a pest contract base is useful only when retention, legal scope and route obligations remain deliverable.
Compare the operating choices →Auto Detailing Business earns from completed scoped vehicle packages and is constrained by technician person-hours, vehicle condition, bay occupation and handover. Residential Remodeling Company earns accepted interior scope, expressed as comparable project equivalents, while controlling a paid carpenter crew and authorized specialty trades. Compare the complete paid operating mechanism and dated cash, using each format’s own unit.
Compare the operating choices →No. The reference is a fixed-site studio. A mobile format needs vehicle investment and running costs, travel time, weather and customer-site constraints.
The BLS vehicle-cleaner occupation is a broad benchmark. It does not establish the wage needed for a particular detailing skill set; replace it with relevant current hiring evidence when researching a local team.
No. It follows the stated labor assumptions and must also fit the bays and package mix. Long jobs, condition exceptions, rework and customer collection delays can lower the usable ceiling.
No states match these filters.
Sorting compares one defined format. It does not rank states for attractiveness or prove demand. Funding includes opening payments, the deepest cumulative operating cash deficit in the 60-month model and the retained cash buffer.
| State | Funding scenario | Loaded payroll / month | Approximate EBIT threshold completed jobs per trading day |
|---|---|---|---|
| Alabama | $52,817 | $5,861 | 2 |
| Alaska | $62,506 | $8,029 | 2.4 |
| Arizona | $57,817 | $7,069 | 2.2 |
| Arkansas | $57,456 | $6,982 | 2.2 |
| California | $60,160 | $7,572 | 2.3 |
| Colorado | $61,888 | $7,908 | 2.4 |
| Connecticut | $58,212 | $7,165 | 2.2 |
| Delaware | $59,669 | $7,476 | 2.3 |
| Florida | $56,150 | $6,667 | 2.1 |
| Georgia | $53,865 | $6,114 | 2 |
| Hawaii | $59,797 | $7,501 | 2.3 |
| Idaho | $58,006 | $7,115 | 2.2 |
| Illinois | $58,246 | $7,173 | 2.2 |
| Indiana | $57,439 | $6,978 | 2.2 |
| Iowa | $58,246 | $7,173 | 2.2 |
| Kansas | $59,584 | $7,460 | 2.3 |
| Kentucky | $57,044 | $6,883 | 2.2 |
| Louisiana | $51,374 | $5,512 | 1.9 |
| Maine | $59,669 | $7,476 | 2.3 |
| Maryland | $58,624 | $7,265 | 2.3 |
| Massachusetts | $60,885 | $7,713 | 2.4 |
| Michigan | $56,562 | $6,766 | 2.2 |
| Minnesota | $59,818 | $7,506 | 2.3 |
| Mississippi | $52,233 | $5,720 | 1.9 |
| Missouri | $57,215 | $6,924 | 2.2 |
| Montana | $58,727 | $7,290 | 2.3 |
| Nebraska | $59,392 | $7,422 | 2.3 |
| Nevada | $56,855 | $6,837 | 2.2 |
| New Hampshire | $59,648 | $7,472 | 2.3 |
| New Jersey | $59,306 | $7,406 | 2.3 |
| New Mexico | $53,607 | $6,052 | 2 |
| New York | $61,674 | $7,867 | 2.4 |
| North Carolina | $56,219 | $6,683 | 2.1 |
| North Dakota | $59,520 | $7,447 | 2.3 |
| Ohio | $57,679 | $7,036 | 2.2 |
| Oklahoma | $54,088 | $6,168 | 2 |
| Oregon | $60,309 | $7,601 | 2.3 |
| Pennsylvania | $57,198 | $6,920 | 2.2 |
| Rhode Island | $59,562 | $7,456 | 2.3 |
| South Carolina | $56,855 | $6,837 | 2.2 |
| South Dakota | $57,525 | $6,999 | 2.2 |
| Tennessee | $57,439 | $6,978 | 2.2 |
| Texas | $52,903 | $5,881 | 2 |
| Utah | $57,404 | $6,970 | 2.2 |
| Vermont | $61,824 | $7,896 | 2.4 |
| Virginia | $57,026 | $6,878 | 2.2 |
| Washington | $62,357 | $8,000 | 2.4 |
| West Virginia | $52,851 | $5,869 | 2 |
| Wisconsin | $57,714 | $7,045 | 2.2 |
| Wyoming | $56,562 | $6,766 | 2.2 |
Published research and calculations support business planning and education. They are not personalized financial, investment, tax or legal advice, and they do not guarantee costs, revenue, profit or financing. Estimates depend on the stated format, location, source periods and assumptions. Check the requirements and commitments that apply to your circumstances.