How many moving jobs are needed to break even?
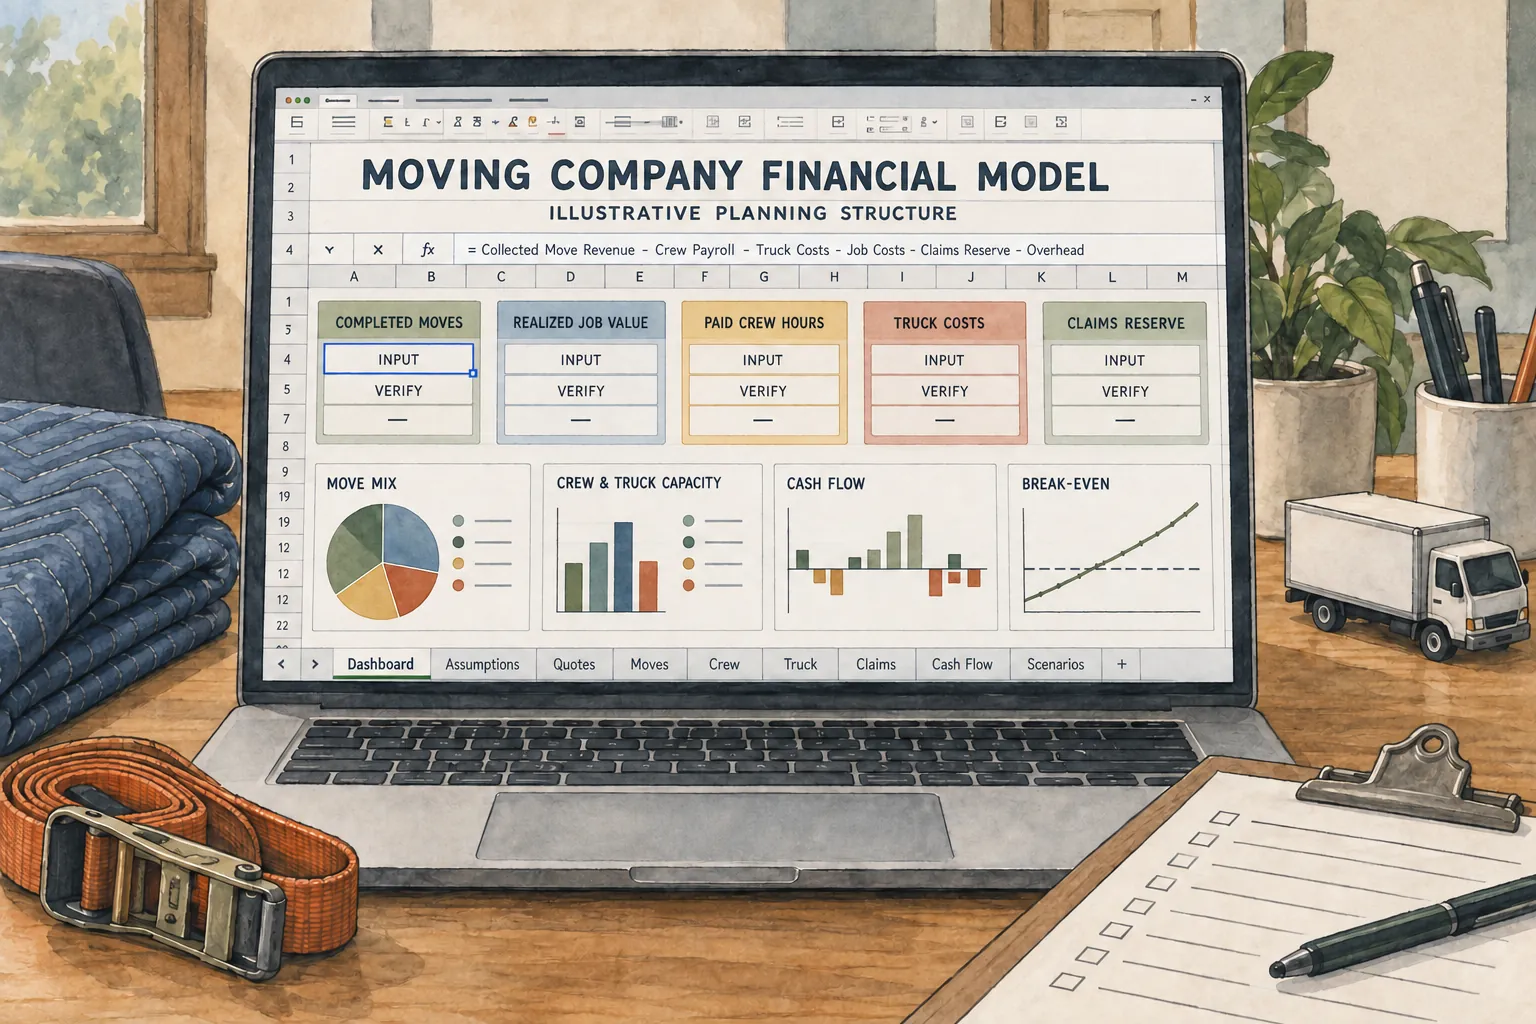
Build realized revenue per move from billable crew-and-truck hours, the realized hourly rate, and any collected travel or dispatch charge. Subtract entered direct move costs, payment fees, and a disclosed claim allowance, then compare contribution with operating EBITDA before maintenance, operating cash after maintenance, and depreciation-inclusive EBIT. Finally, round break-even up to whole moves and confirm that the count fits both paid crew-hours and usable truck-hours after nonjob time and claim recovery.
What you will produce: Realized revenue and contribution per move, three labeled monthly results, whole-move break-even for each boundary, crew-hour gap, truck-hour gap, lower physical capacity, and the signed gap between physical capacity and EBIT break-even.
Updated September 21, 2026 · Worked examples and editable worksheets
What to have ready
Bring completed-move records, inventory and access assumptions, quote or estimate basis, realized billable hours, hourly crew-and-truck rate, travel or dispatch charges, discounts and refunds, direct fuel, toll, parking and material costs, payment fees, paid roster, employer allowance, truck and insurance cost, parking or storage, maintenance, depreciation, paid crew-hours, paid truck-hours, nonjob time, claims tied to original moves, and collection dates.
Work through the calculation and decision
What counts as a completed local move?
Count one move when the included origin-to-destination household work and customer handoff satisfy the stated completion and revenue policy, and keep collection status visible. A lead, estimate, reservation, deposit, cancellation, reschedule, unfinished move, disputed invoice, claim, refund, chargeback, or recovery visit is not another completed move.
Keep inventory and access assumptions, quote basis, billable hours, hourly rate, travel or dispatch charge, paid crew-hours, truck-hours, direct costs, collection, and claim outcome attached to the same move. Use an average only after the underlying closed-move records remain visible.
How should move pricing enter break-even?
Calculate revenue per move from realized billable crew-and-truck hours and the realized rate, plus any collected travel or dispatch charge. Subtract only costs that vary with the move, payment fees, and the entered claims allowance. Paid roster wages belong in monthly payroll and must not be counted again per move.
Compare monthly contribution with three explicit boundaries. Operating EBITDA excludes the separate maintenance reserve and depreciation. Operating cash after maintenance adds the reserve. Depreciation-inclusive EBIT adds depreciation instead. Owner withdrawals, debt service, income tax, major fleet replacement, and unentered costs remain outside all three.
Why must crew and truck capacity be tested separately?
Deduct yard work, estimates, training, breaks, documentation, idle gaps, claim recovery, and other entered nonjob time from paid crew-hours. Reconcile usable truck-hours after inspection, fueling, cleaning, maintenance, idle time, ordinary downtime, and claim recovery. A profitable count is infeasible when either schedule cannot deliver it.
Round financial break-even up to whole moves, then compare it with the lower whole-move ceiling from crew and truck time. Preserve the signed gaps instead of silently reducing the entered demand. Investigate inventory, access, travel, quoting, and claims when actual job time exceeds the plan.
The reference plan produces $34,578.50 of monthly contribution before the paid roster and standing costs
This authored scenario uses 22 completed local moves, 6.50 realized billable crew-and-truck hours per move, and a $270.00 hourly crew-and-truck rate. Prices, hours, direct costs, claims, route time, access, truck terms, and completed demand are planning assumptions rather than observed national or local performance.
| Input or result | Calculation | Reference |
|---|---|---|
| Realized revenue per move | 6.50 hours × $270.00 + $95.00 charge | $1,850.00 |
| Monthly move revenue | 22 moves × $1,850.00 | $40,700.00 |
| Monthly contribution | Revenue − direct move cost − payment fees − claims allowance | $34,578.50 |
| EBITDA boundary before maintenance | Loaded payroll + truck standing cost + parking or storage + other standing costs | $29,227.48 |
| Operating EBITDA | $34,578.50 − $29,227.48 | $5,351.02 |
| Cash after maintenance | $34,578.50 − $30,727.48 | $3,851.02 |
| Depreciation-inclusive EBIT | $34,578.50 − $30,694.15 | $3,884.35 |
| Whole-move EBIT break-even | $30,694.15 ÷ $1,571.75 = 19.53; round up | 20 moves |
| Crew-hour gap | 474.40 productive − 429.00 direct | 45.40 hours |
| Truck-hour gap | 160.80 productive − 143.00 direct | 17.80 hours |
| Physical capacity | Lower of crew and truck whole-move ceilings | 24 moves |
What this changes: The authored plan fits depreciation-inclusive break-even inside the entered physical capacity, with a signed gap of 4 moves. Replace billed hours, realized rate, direct costs, nonjob time, access, claims, truck availability, and completed demand with actual records before making a commitment.
Test Moving Company pricing, break-even, crew time and truck capacity
Start with the illustrative example, then replace its inputs with your own assumptions. All money amounts are in USD. The result updates in this tab.
Illustrative result · assumptions apply
- Realized revenue per completed move
- $1,850.00
- Monthly completed-move revenue
- $40,700.00
- Monthly direct move, payment and claims cost
- $6,121.50
- Contribution per completed move
- $1,571.75
- Combined monthly contribution
- $34,578.50
- Loaded monthly payroll
- $17,527.48
- Operating EBITDA cost boundary
- $29,227.48
- Cash-after-maintenance cost boundary
- $30,727.48
- Depreciation-inclusive EBIT cost boundary
- $30,694.15
- Monthly operating EBITDA result
- $5,351.02
- Monthly cash result after maintenance
- $3,851.02
- Monthly depreciation-inclusive EBIT result
- $3,884.35
- Exact EBITDA break-even moves
- 18.6 moves
- Whole EBITDA break-even moves
- 19 moves
- Exact cash break-even moves
- 19.55 moves
- Whole cash break-even moves
- 20 moves
- Exact EBIT break-even moves
- 19.53 moves
- Whole EBIT break-even moves
- 20 moves
- Entered claim incidents
- 1.1 incidents
- Productive crew-hours after nonjob and claim time
- 474.4 crew-hours
- Direct crew-hours required by entered moves
- 429 crew-hours
- Remaining crew-hour capacity; negative means overbooked
- 45.4 crew-hours
- Productive truck-hours after nonjob and claim time
- 160.8 truck-hours
- Direct truck-hours required by entered moves
- 143 truck-hours
- Remaining truck-hour capacity; negative means overbooked
- 17.8 truck-hours
- Crew-supported whole-move capacity
- 24 moves
- Truck-supported whole-move capacity
- 24 moves
- Lower physical whole-move capacity
- 24 moves
- Physical capacity minus whole EBIT break-even
- 4 moves
Whole-move EBIT break-even fits inside the entered crew-and-truck capacity. A reservation, deposit, claim or recovery visit is not another completed move. Paid roster wages remain in monthly payroll and are not counted again per move. The claims allowance and recovery time are entered sensitivities unless closed-move records support them. This is an authored scenario, not observed demand or a guarantee.
Complete your decision record
Realized revenue and contribution per move, three labeled monthly results, whole-move break-even for each boundary, crew-hour gap, truck-hour gap, lower physical capacity, and the signed gap between physical capacity and EBIT break-even. Enter the finding or number, the source and the next action for each row. “Supported” records your assessment of that item; it does not approve the business or certify completed research.
| Item and what to record | Your finding and evidence | Status and next action |
|---|---|---|
| Move ledgerMove ID, origin, destination, inventory and access, estimate or quote, billable basis, paid hours, truck-hours, direct costs, realized charge, collection, and claim outcome | ||
| Paid capacityCrew-hours and truck-hours by yard, deadhead, customer work, travel, closeout, reset, maintenance, idle, and claim recovery | ||
| Cost boundaryLoaded payroll, truck standing cost, parking or storage, other standing costs, maintenance reserve, depreciation, and selected exclusions | ||
| Claims and refundsOriginal move, notice, evidence, reserve, paid recovery work, truck use, repair or replacement, recovery, refund, customer outcome, and closure | ||
| DecisionSelected financial boundary, whole-move threshold, crew gap, truck gap, and the next price, scope, route, quality, or funding test |
5 items have no evidence recorded yet.
Entries are temporary and are not sent to us or saved automatically. Download your completed work before leaving or refreshing this page.
Choose your next action
| If your finding is… | Your next action |
|---|---|
| Break-even exceeds crew capacity | Change price, scope, direct cost, nonjob time, claims, roster, or commitments before adding demand. |
| Break-even exceeds truck capacity | Change schedule, route, job duration, downtime, truck plan, or accepted workload before promising the work. |
| Price works only with unsupported billable hours or charges | Retest the exact quote and customer terms rather than treating the calculated price as achieved revenue. |
Errors that can change the result
- Using a reservation, deposit, or claim recovery as another completed move.
- Counting paid crew wages in monthly payroll and again inside direct cost per move.
- Calling an operating result owner income, debt capacity, or investment payback.
Apply this to your business
These operating formats match the decisions in this guide.
Moving Company
Local household moving company with one straight or box truck, one paid three-person field crew, paid owner-manager and dispatch coverage, ordinary moving equipment, secure overnight parking or storage, and a defined local service area
Open the operating guide and state profiles →Carry the completed-move policy, realized price, whole-move threshold, crew and truck capacity, claims, and selected cost boundary into the opening plan and state reference pages. Values entered here are not automatically transferred to another calculator.
Continue with the next part of your plan
- How to plan moving dispatch, loading, travel, and claims
A weekly one-truck dispatch board, scope-and-readiness check, crew-hour and truck-hour reconciliation, access and parking record, loading and customer-property controls, claim ledger, and conditional decision about price, service area, accepted work, staffing, or truck commitment.
- How to price a service and cover the work behind it
A tested price, contribution per completed sale and the sales needed to cover monthly fixed costs.
- How to build a staffing roster before estimating payroll
A roster with complete task coverage and an annualized monthly staffing budget.
- How to build a 13-week cash plan for your first 90 days
A weekly cash schedule, the lowest balance and the extra funding needed to retain your chosen minimum.
Sources and limits
The sources below provide the stated background. The worked examples, calculator defaults and decision exercises are authored teaching material. They do not establish market prices, local demand, legal applicability or completed state research.
- U.S. Census Bureau: NAICS 484210 Used Household and Office Goods Moving
The industry includes office moving and operators larger than the one-truck household format. Establishment, employment, payroll and receipt totals do not establish local demand, a realized move ticket or a company forecast.
- BLS May 2025 Occupational Employment and Wage Estimates
Cross-industry wage anchors for the disclosed driver or crew-lead, mover or helper and paid manager or dispatch roles; not hiring quotes, overtime estimates, owner draws or complete employer costs.
- FMCSA Protect Your Move: household-goods consumer and carrier framework
Federal household-goods rules apply by stated federal scope, including interstate moves. Intrastate authority, estimates, tariffs, insurance, vehicle, labor, parking and claims requirements require current state and local checks for the selected operation.
Source pages checked September 21, 2026. Research and review standards · Report an issue
When you need a longer financial plan
Use a financial model to organize a broader forecast after defining your own operating assumptions. The site’s research, your worksheet entries and any purchased workbook are separate; entries are not transferred automatically.
Continue with the published financial scenario